Finexer Open Banking Blogs
UK Transaction Data Enrichment API: Pricing & Accuracy
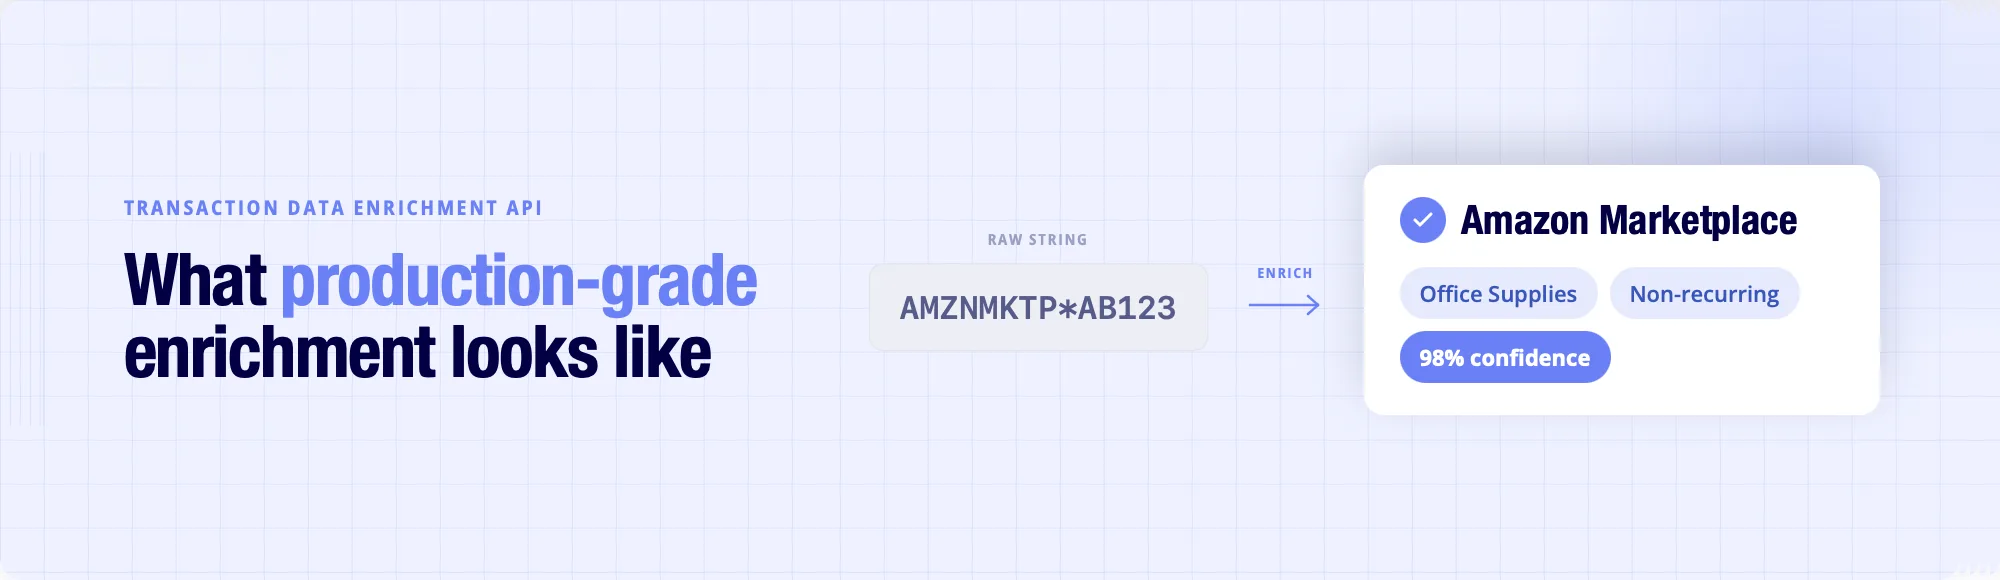
“AMZNMKTP*AB123” tells your reconciliation engine nothing. A transaction data enrichment API turns that string into Amazon Marketplace, Office Supplies, non-recurring, in one API call. This guide covers merchant-match accuracy, data enrichment API pricing models, structured JSON schema across UK banks and what separates production-grade enrichment from a categorisation feature bolted onto a data feed.
International Payments Still Break at Scale. Here Is Why.
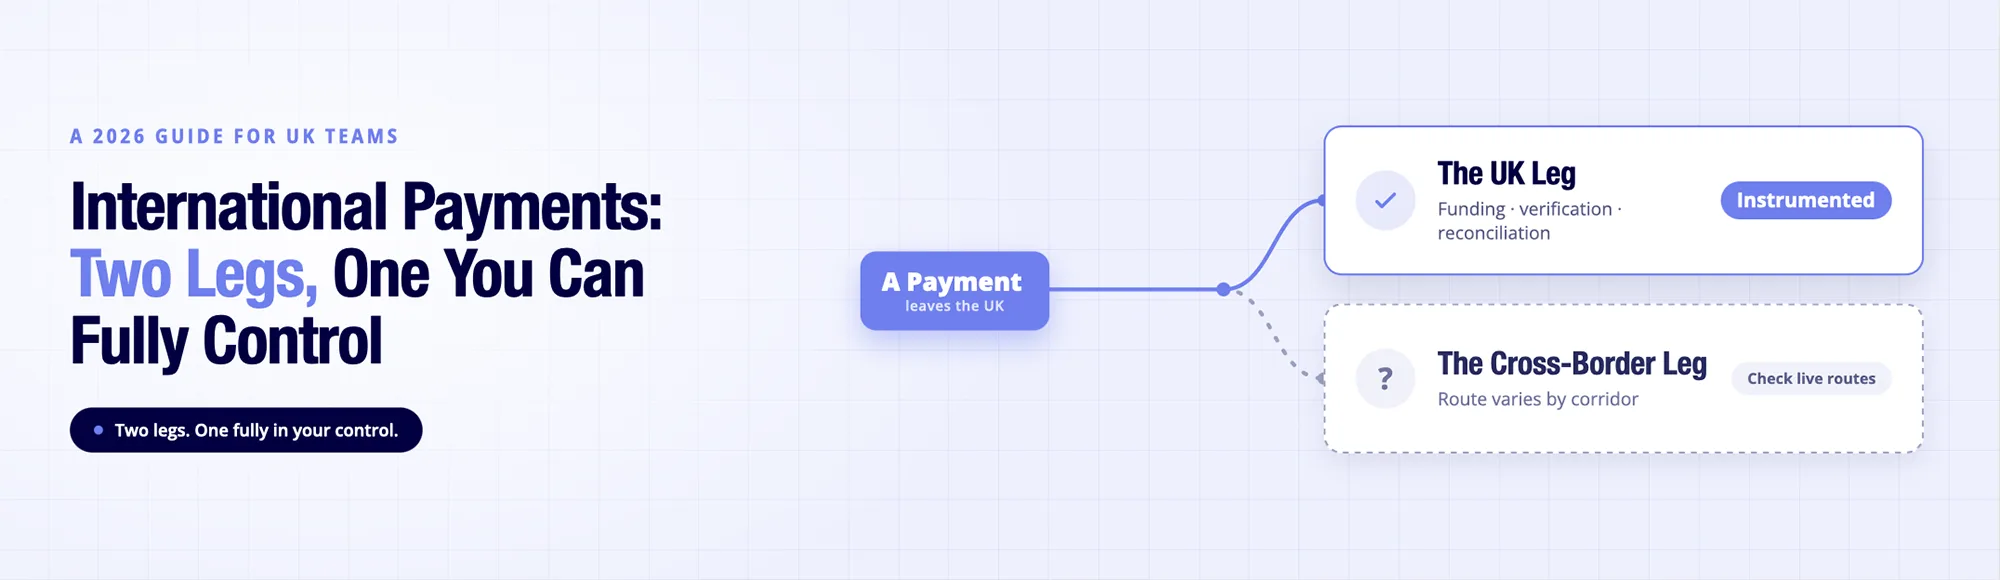
International payments from the UK are two journeys joined together: a fast domestic leg and a slower cross-border leg where fees and visibility hide. This guide explains how each leg works, the four real costs, what Open Banking can and cannot change, and how to compare international payout services properly.
Payment Status Tracking: Webhooks vs Polling and the Open Banking Approach
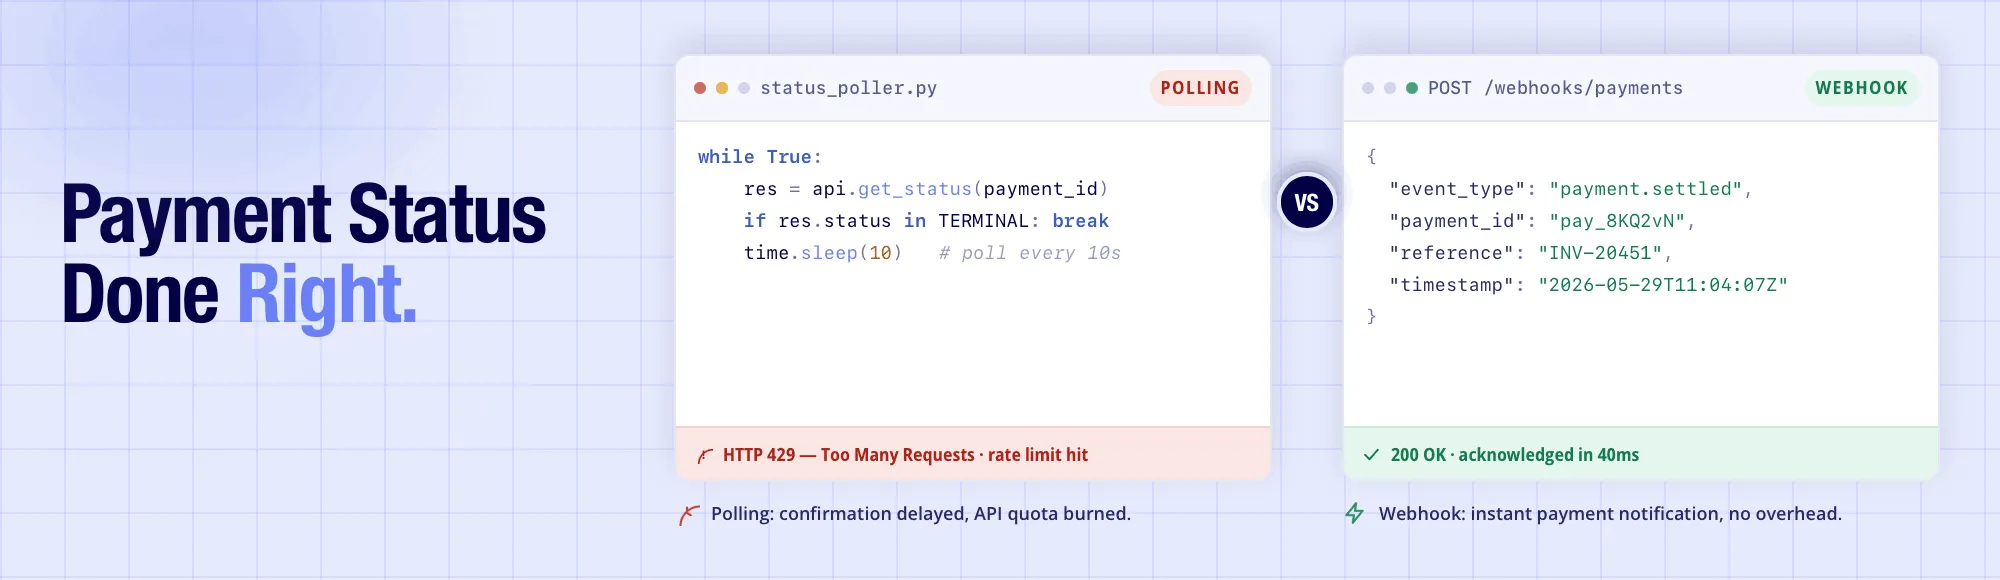
Payment status is one of those things that looks simple until you are running payment workflows at volume on a UK platform. Polling creates rate limit pressure, confirmation delays, and reconciliation gaps that compound with scale. This is how webhooks, idempotency, and bank-confirmed instant payment notification change the operational picture for engineering and product teams.
Banking statement API data: What actually returned ?
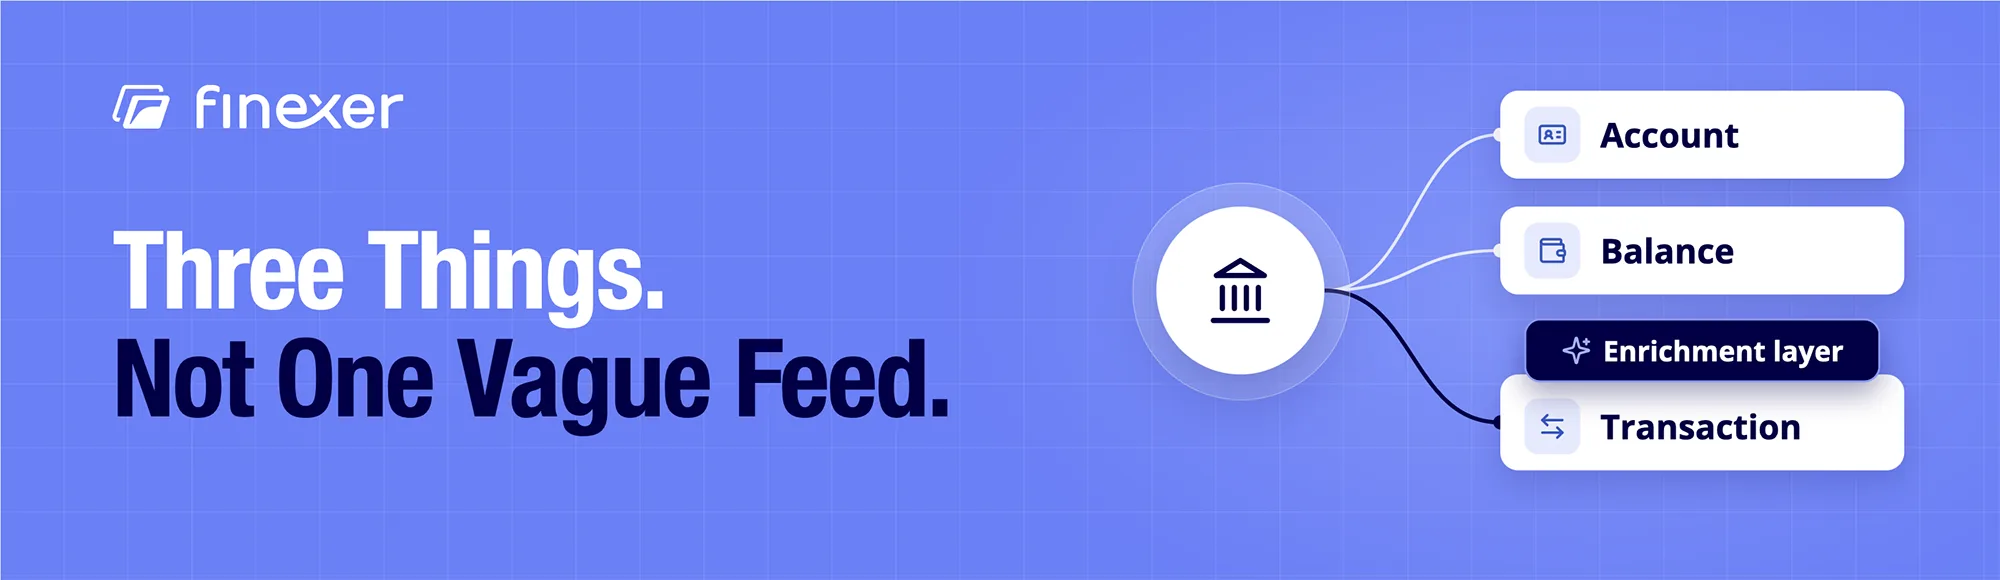
Banking statement api data is not one single thing. A UK Open Banking connection returns account data, balance data and transaction data, structured through the same consented request rather than parsed from a document. This article covers what each type actually contains and what a platform can build once a document is no longer needed.
How accurate is automated transaction categorisation?
Transaction categorisation accuracy depends on more than a headline percentage. This guide explains how merchant coverage, transaction descriptors, test sets and use cases affect results and how transaction enrichment can add context. Learn what to test, what accuracy means in practice and which questions to ask before choosing an automated categorisation provider for your product.
How Do You Detect Fake or Edited Bank Statements?
Fake bank statement detection by eye catches only obvious cases: mismatched fonts, totals that visibly do not add up correctly. A competent edit passes most manual checks without much trouble. This article covers what manual review actually catches, why a document is structurally weak, and what changes once data comes straight from the bank instead.
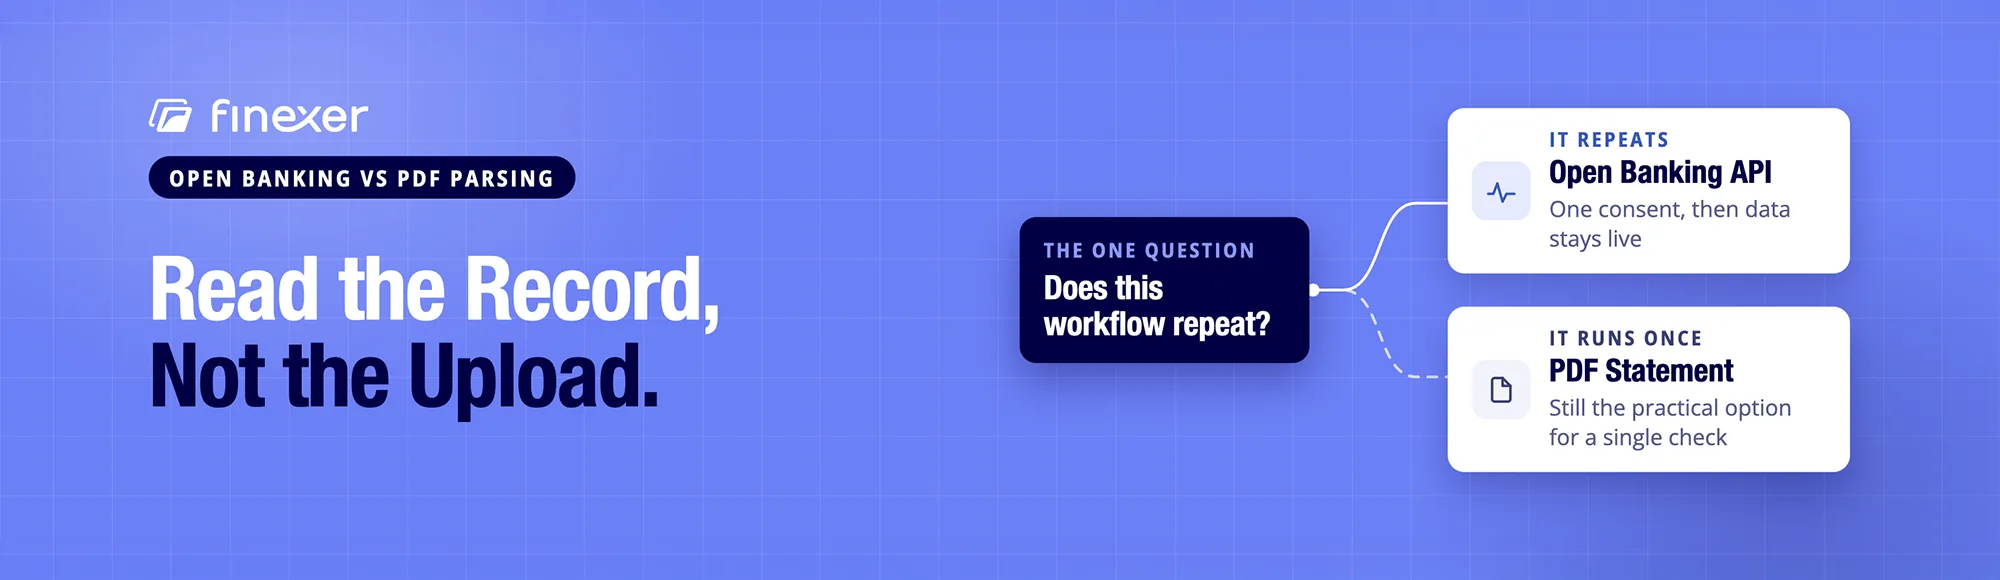
Open Banking vs PDF Bank Statement Parsing: Which Should We Use?
Open banking vs bank statement parsing is not a close call for a workflow that genuinely repeats month after month. PDF parsing depends on a document a customer has to find, download and upload, one that can be edited before it ever reaches you. This article compares both methods on accuracy, effort and completion rate.
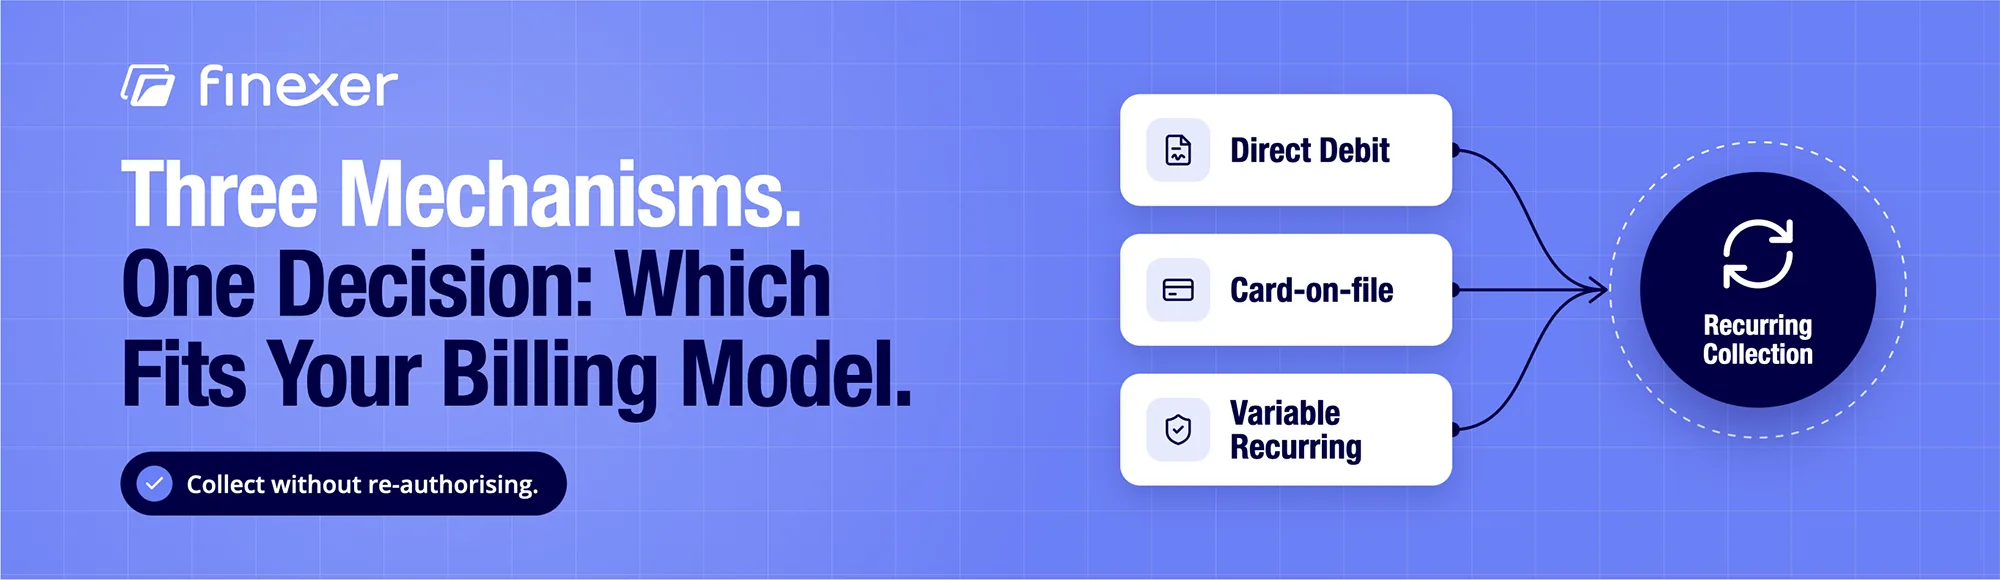
Recurring Payment Solutions: 3 UK Options Compared
Compare recurring payment solutions for UK subscriptions, billing platforms, proptechs and financial organisations. This guide compares Direct Debit, card-on-file and variable recurring payments across setup, amount flexibility, customer control, payment failures, settlement and reconciliation. Find the right collection method for fixed, variable, usage-based, high-value and irregular billing models.
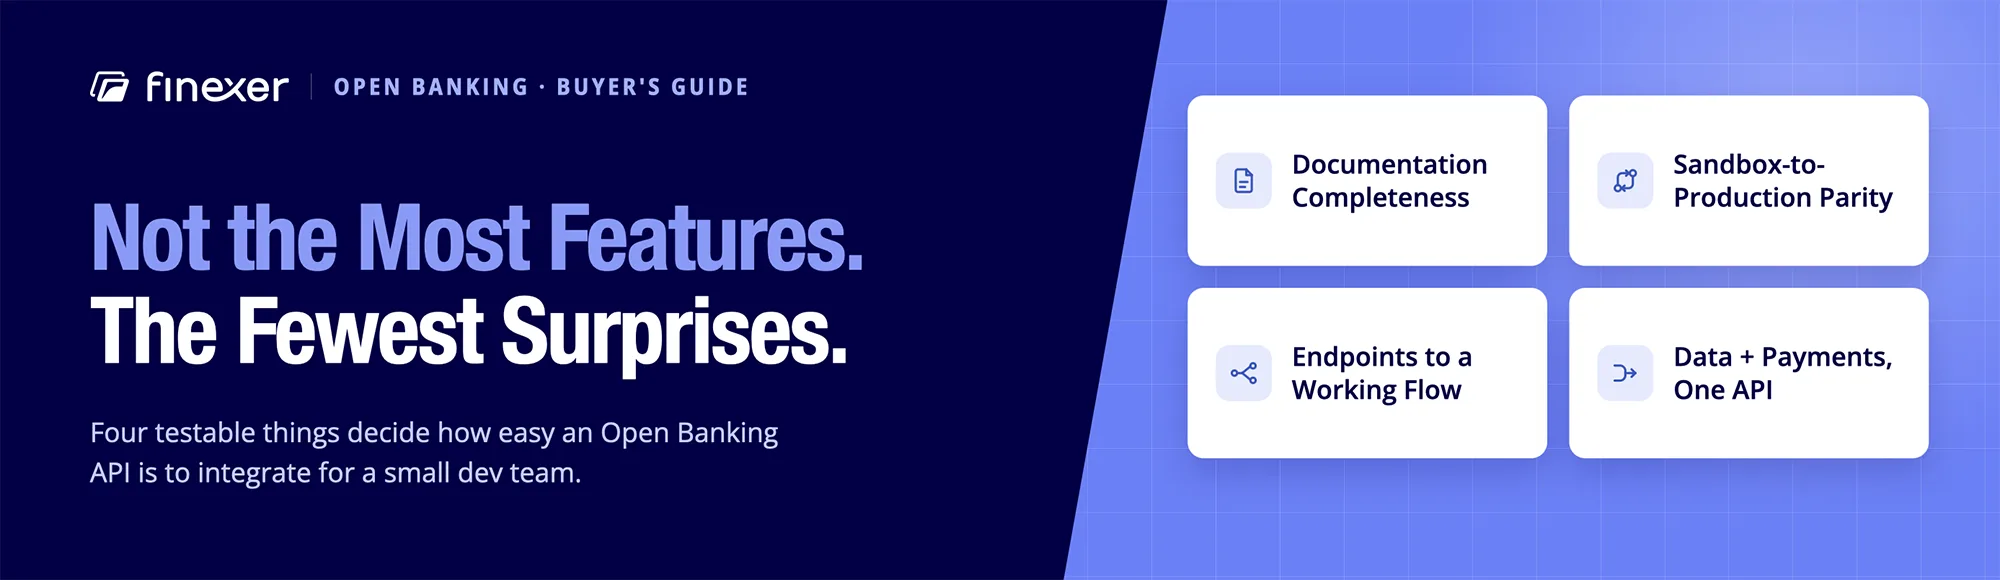
Which Open Banking APIs are easiest to integrate for a small dev team?
Ease of integration comes down to four testable things: documentation, sandbox parity, endpoint count, and whether data and payments sit in one API. Here’s a practical framework for evaluating the easiest open banking api for a small dev team, before committing build time.
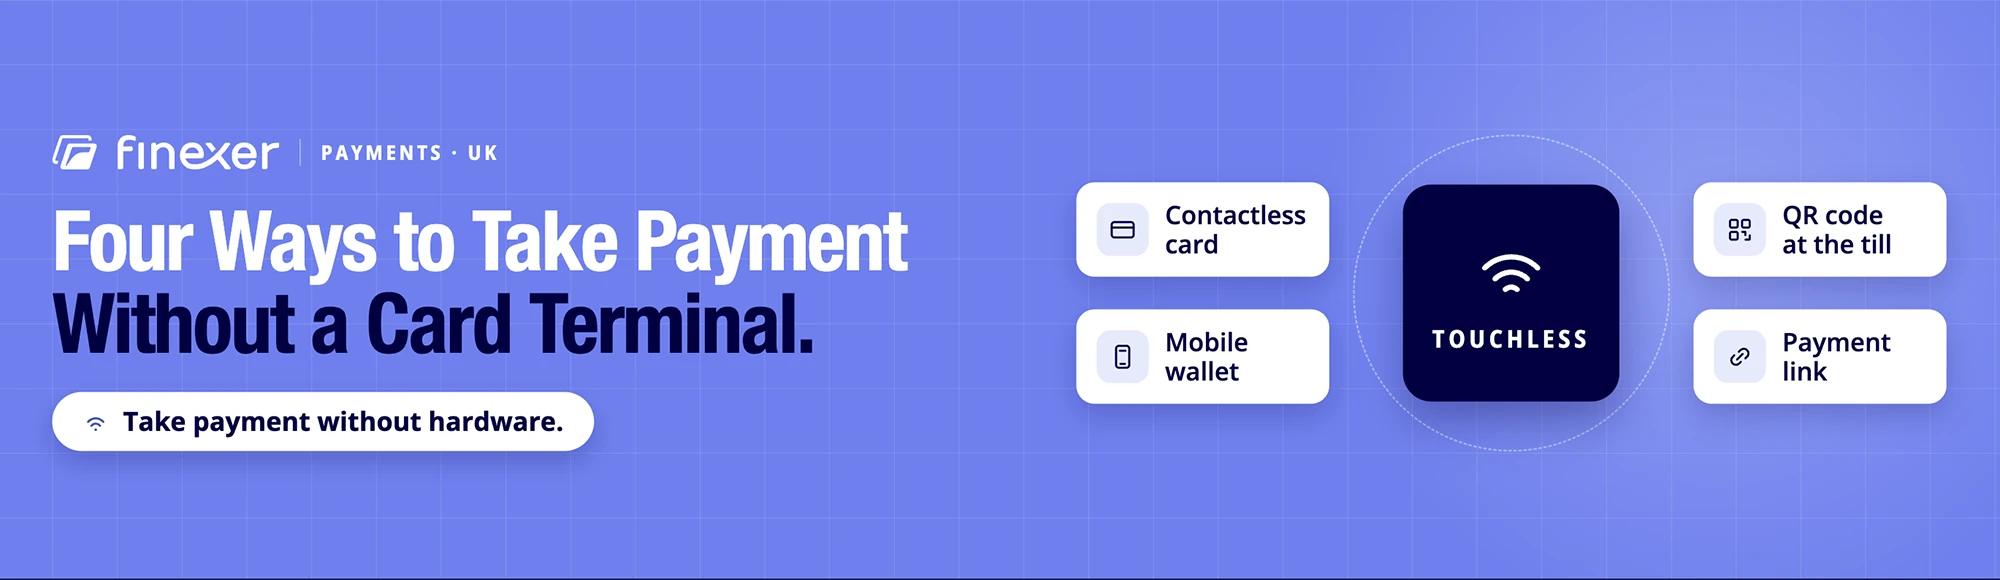
Touchless Payment Options: Best Methods for UK Firms
Touchless payment options let customers pay without handling a terminal or entering card details manually. This guide compares contactless card, mobile wallet, QR-initiated bank payment, and payment link methods on cost, settlement, and sector fit, with the honest limitations of each, so UK merchants can decide which flexible payment options suit their customers best.
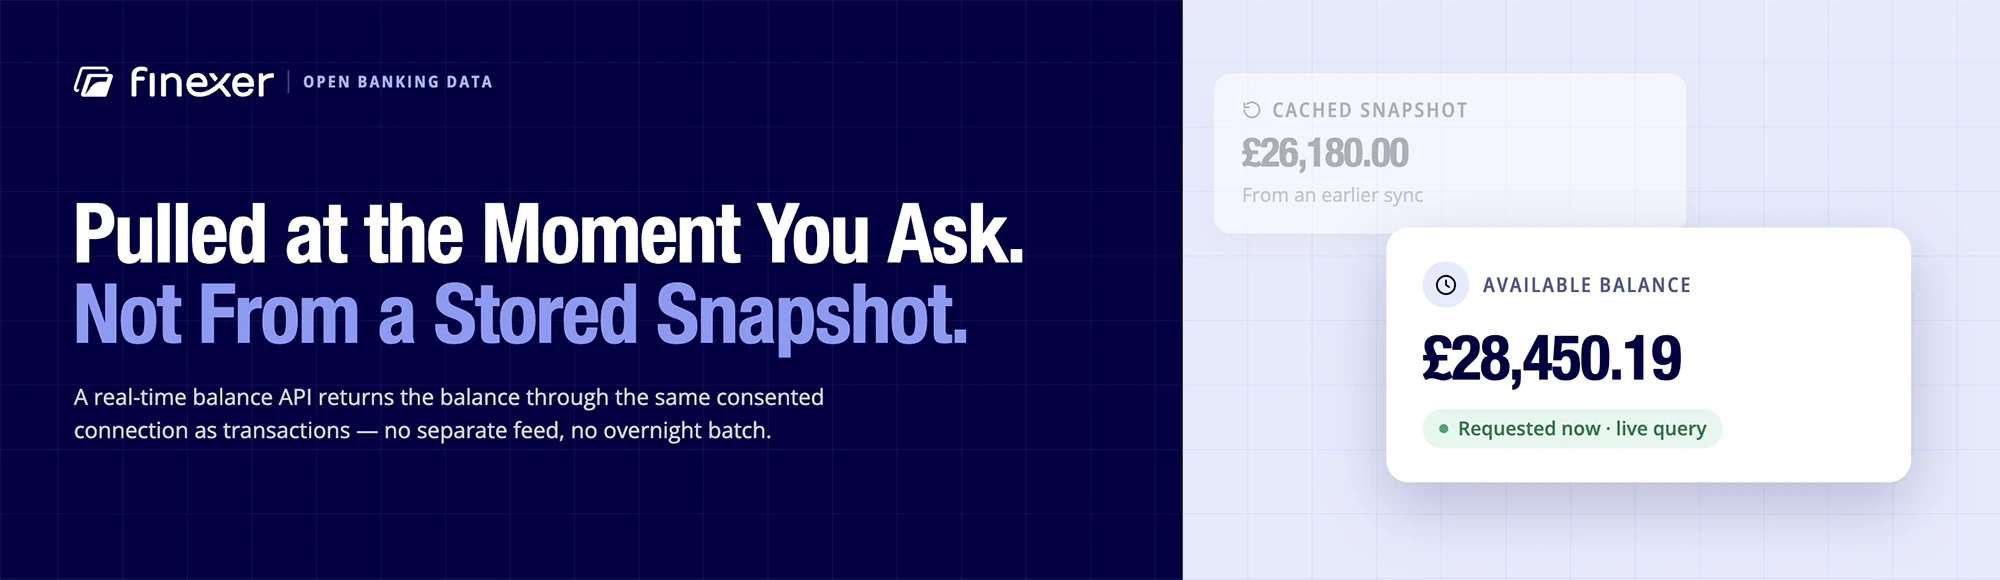
How Can I Get Real-Time Balance Information From a UK Bank Account?
A real-time balance API returns balance data through the same consented connection used for transactions, pulled at the moment you request it rather than from an earlier stored snapshot, not a cached one. This article covers why current and available balances differ, where platforms actually use live balance checks and how providers actually compare.
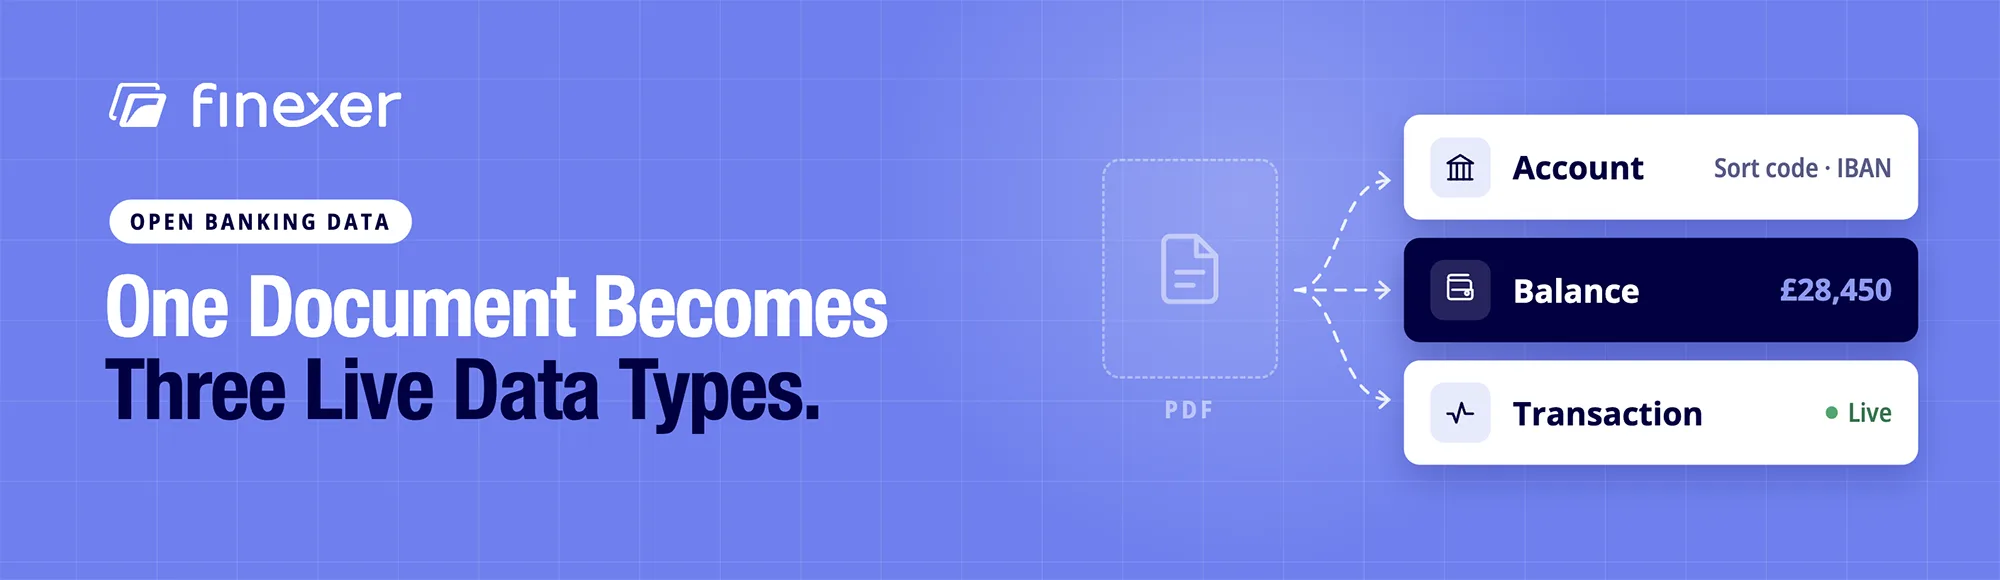
Can You Get Banking Statement Data Digitally Instead of PDF Uploads?
Digital banking statement data comes straight from the bank through an API once a customer gives their consent, with no document to find, download or upload. This article covers the three data types that replace a PDF, why statement uploads cause drop-off on mobile, and where a document still has a genuine job to do.
Which UK Open Banking providers offer both data and payments in one API?
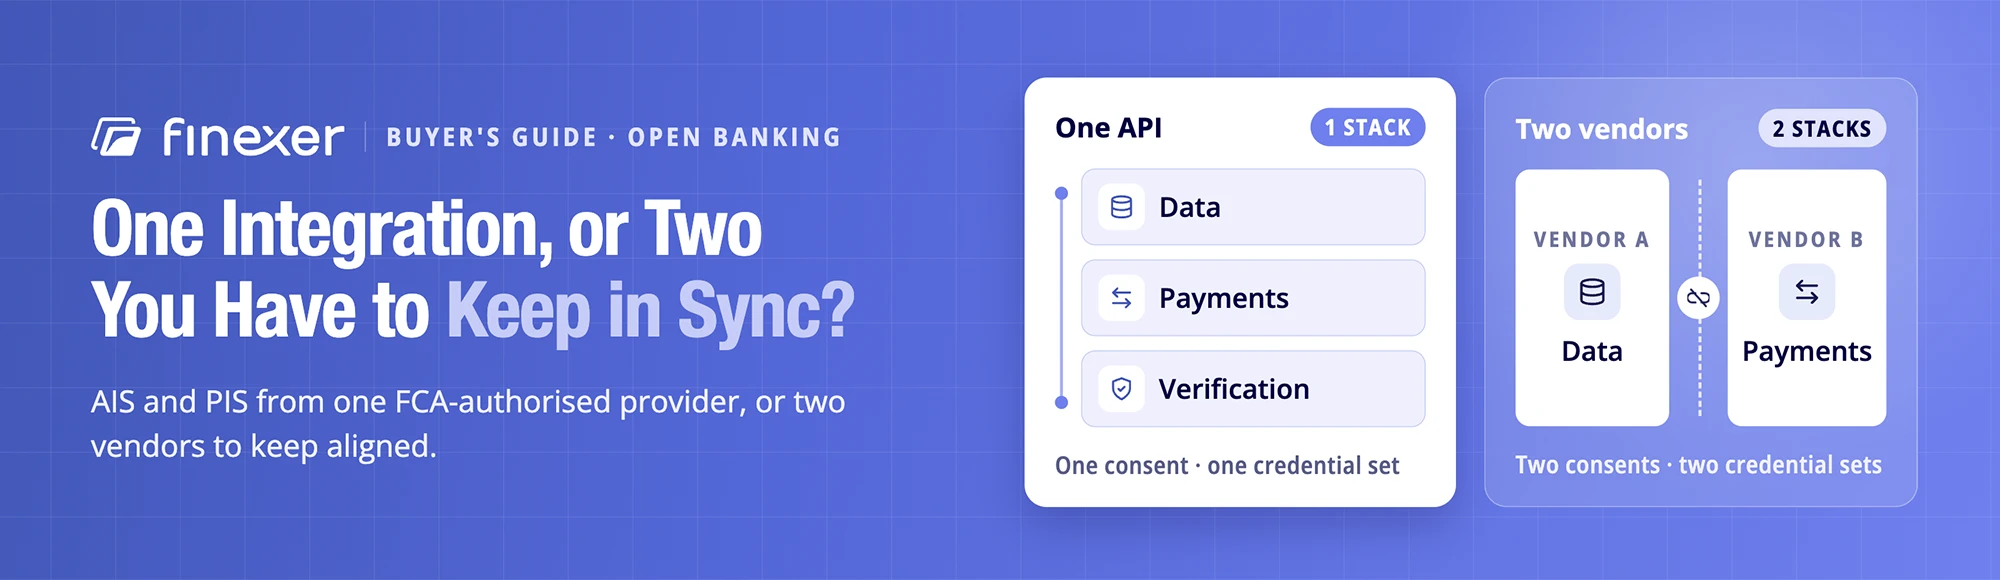
Some UK Open Banking providers combine data access and payment initiation in one API; others require separate contracts. Here’s what a split stack actually costs in engineering time, when it’s genuinely fine, and how a single integration changes consent, credentials and support.
Does Finexer cover UK business and challenger accounts?
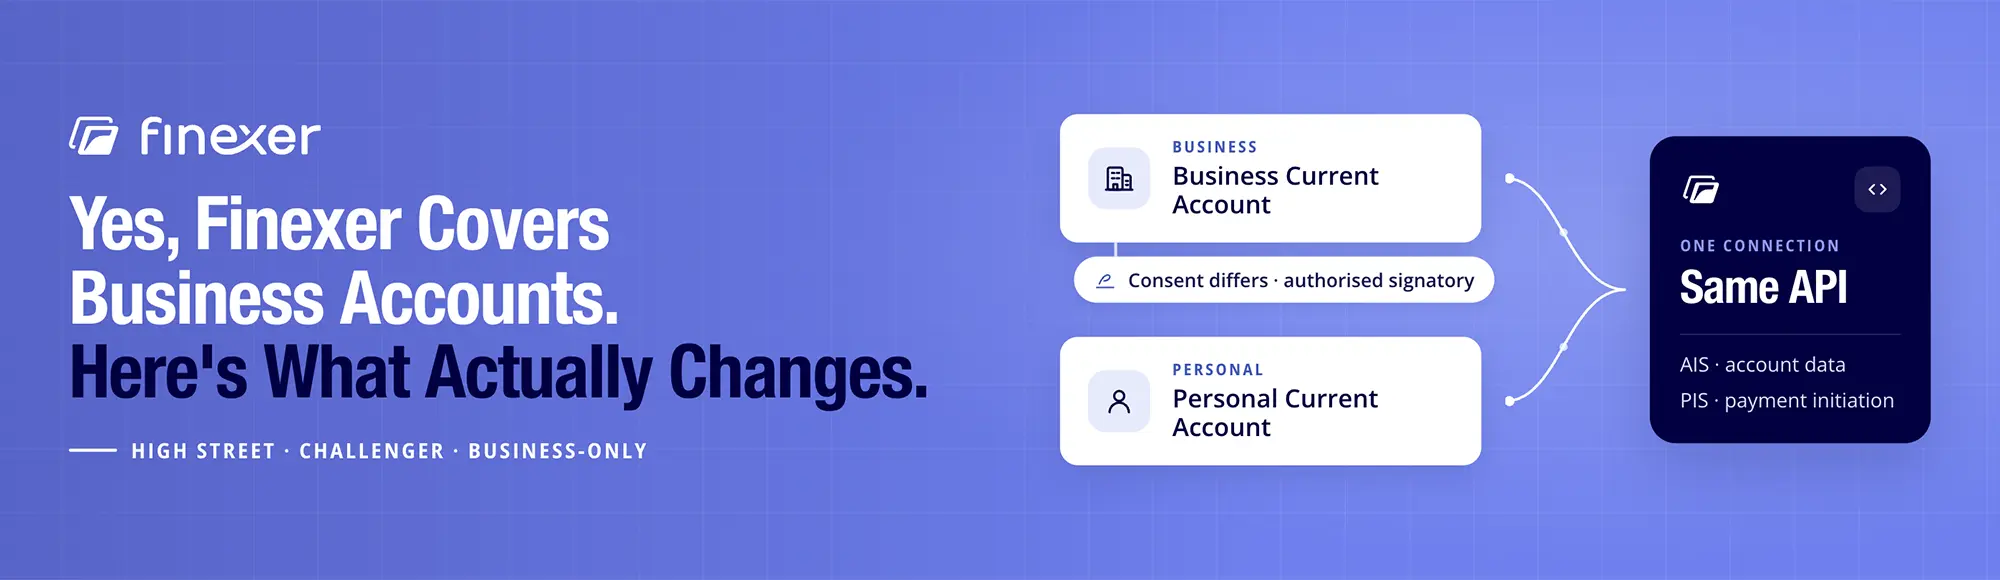
Yes, business bank account open banking through Finexer covers business current accounts across high street, challenger, and business-only providers. Here’s what differs from personal accounts: signatory consent, multi-user structures, and mandate rules, plus the exact account types covered and 2026 usage data.
How Accurate Is Open Banking Data Compared to Uploaded Bank Statements?
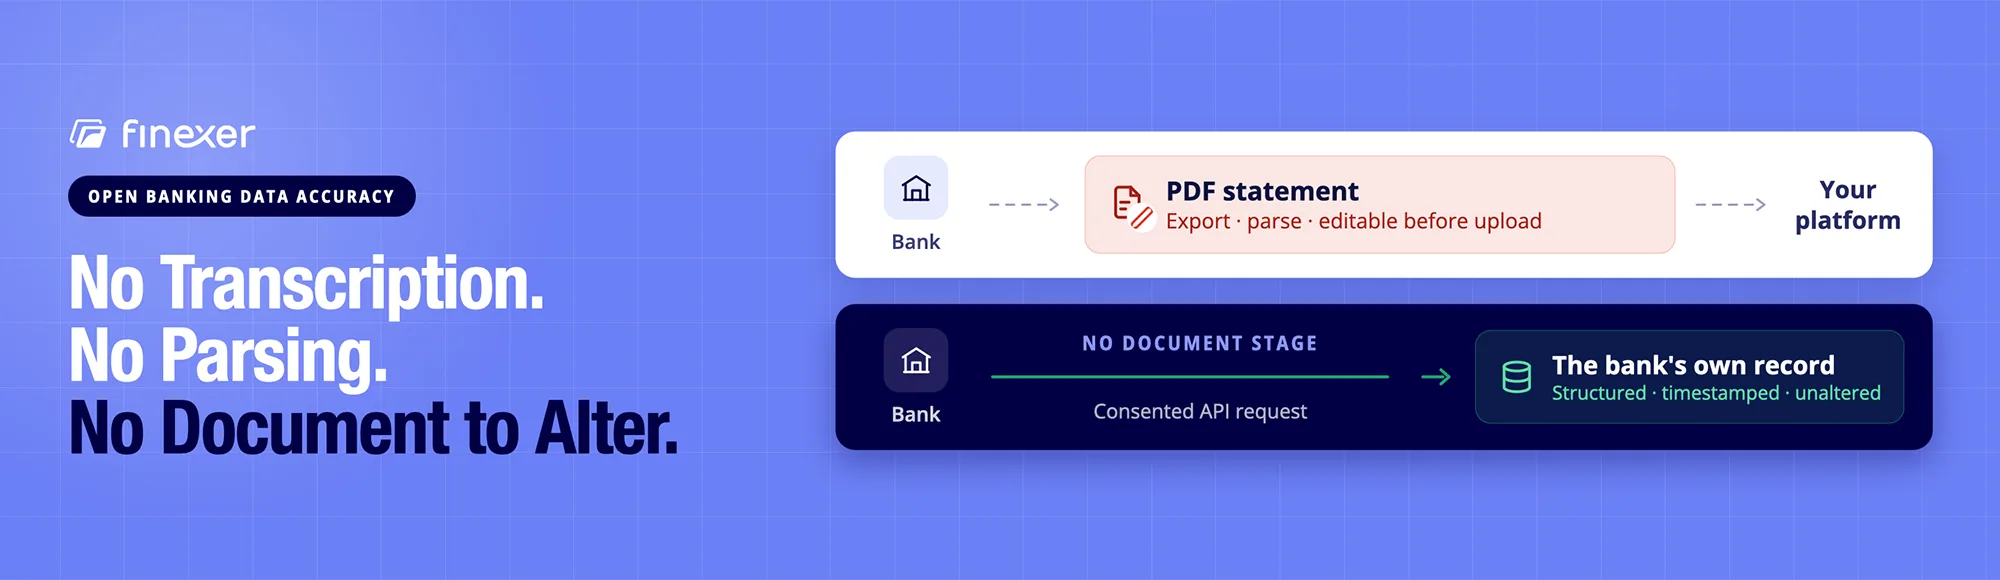
Open banking data accuracy comes from the bank’s own record, with no transcription step, no parsing tool, and no document that can be altered before it reaches you. An uploaded PDF statement has already passed through both. This article compares the two on accuracy, completeness and audit trail, then covers what API data still needs.
How Do Apps Turn Messy Bank Transaction Strings into Merchant Names?
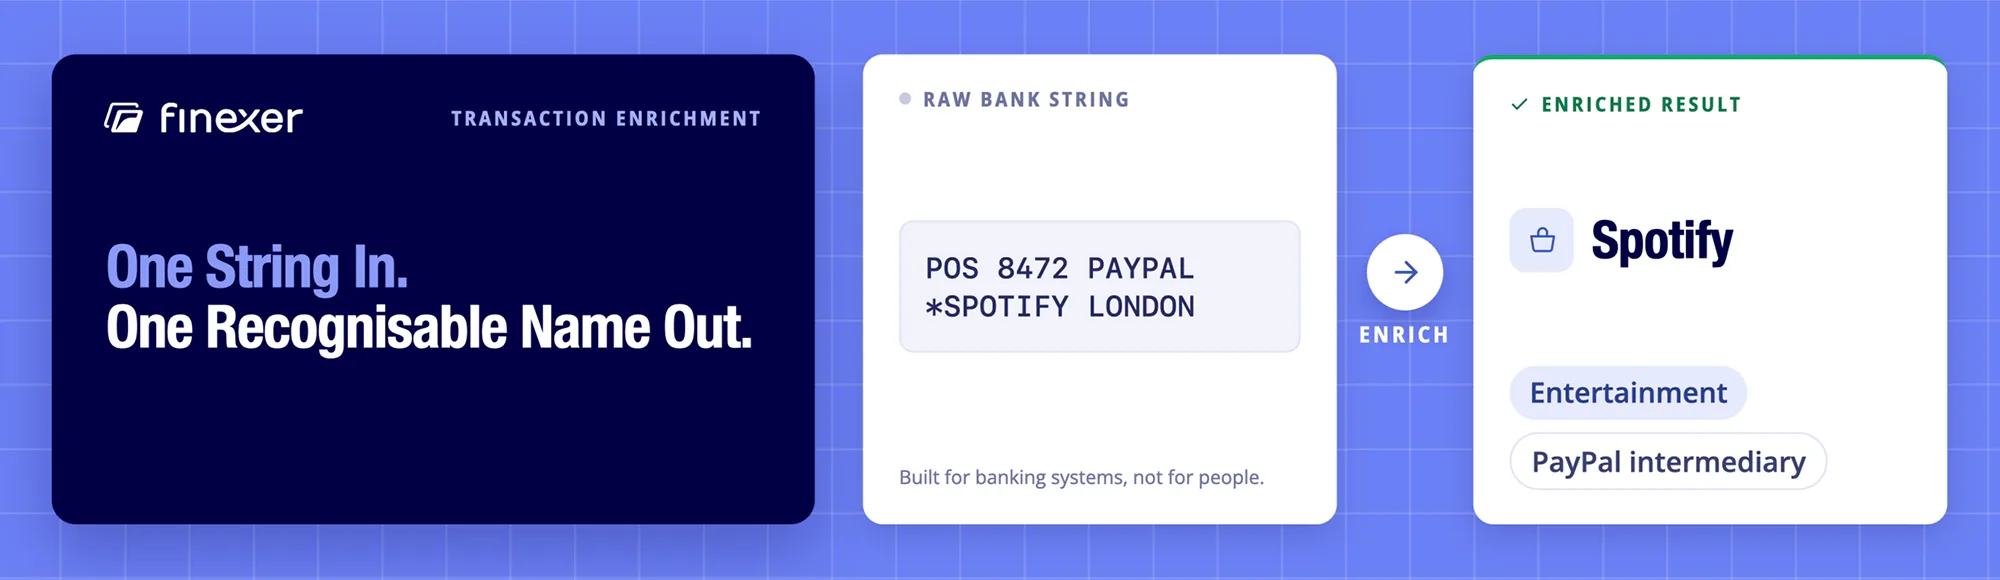
Bank transaction strings like POS 8472 PAYPAL SPOTIFY LONDON mean little to a user. Merchant name enrichment matches these strings against merchant intelligence to return a recognisable name, category and confidence score. This article covers how transaction enrichment actually works, how providers compare and exactly where Finexer fits for platforms already using Open Banking connectivity.
PFM Meaning: What Personal Financial Management Actually Covers
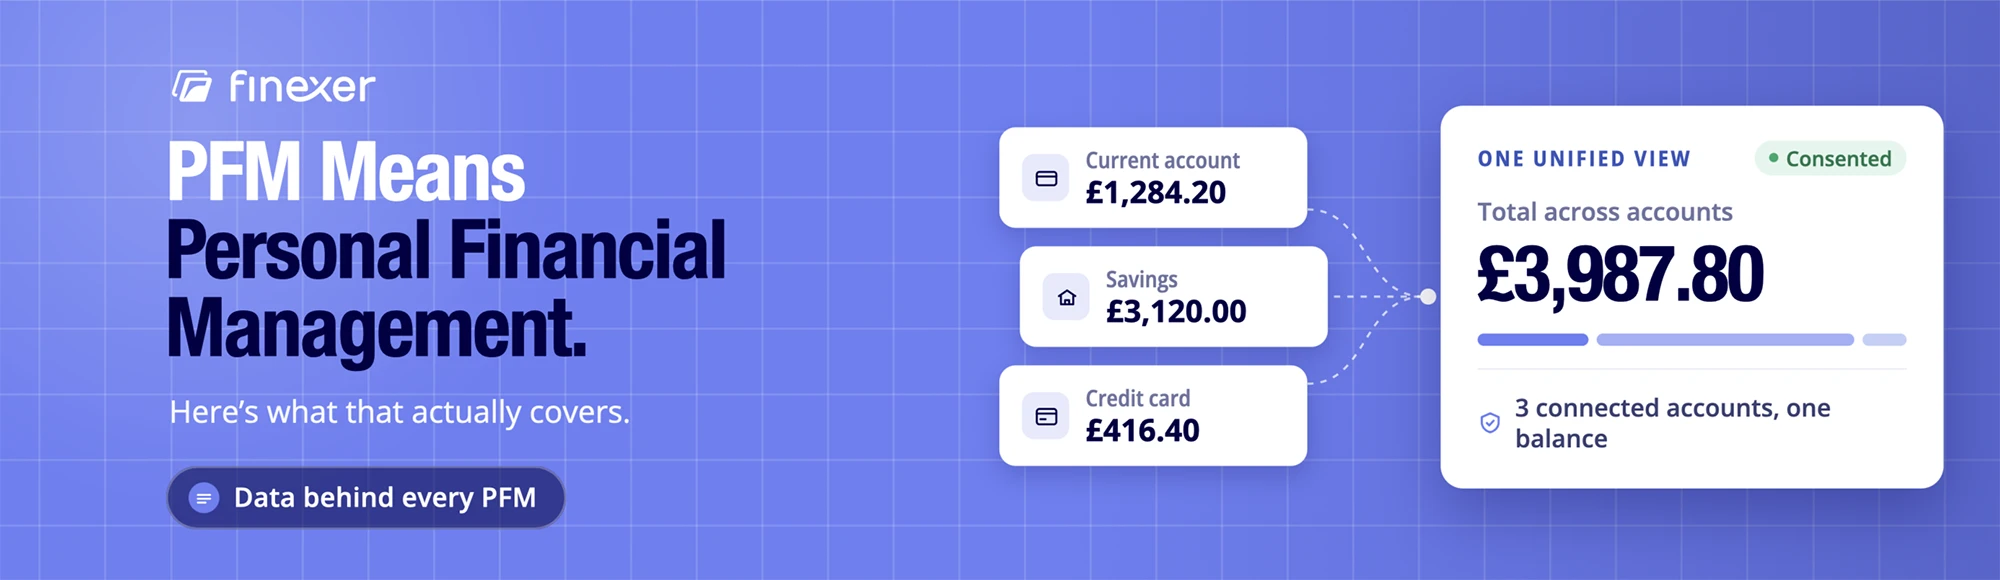
PFM, meaning Personal Financial Management, is a category of tools bringing forth account balances, categorising everyday spending and flagging upcoming bills before they land. This guide’s coverage extends to what PFM represents, ways a PFM tool reads banking data behind the scenes and the needs that a platform may have before it properly builds one.
Which Open Banking provider has the best UK bank coverage?
Headline bank counts look impressive but tell you little about real open banking bank coverage. The differences that matter sit in business accounts, challenger banks, and connection reliability. Here’s what to ask a provider before choosing, and where common coverage gaps actually appear.
Extract Data From Bank Statements: Best UK Methods
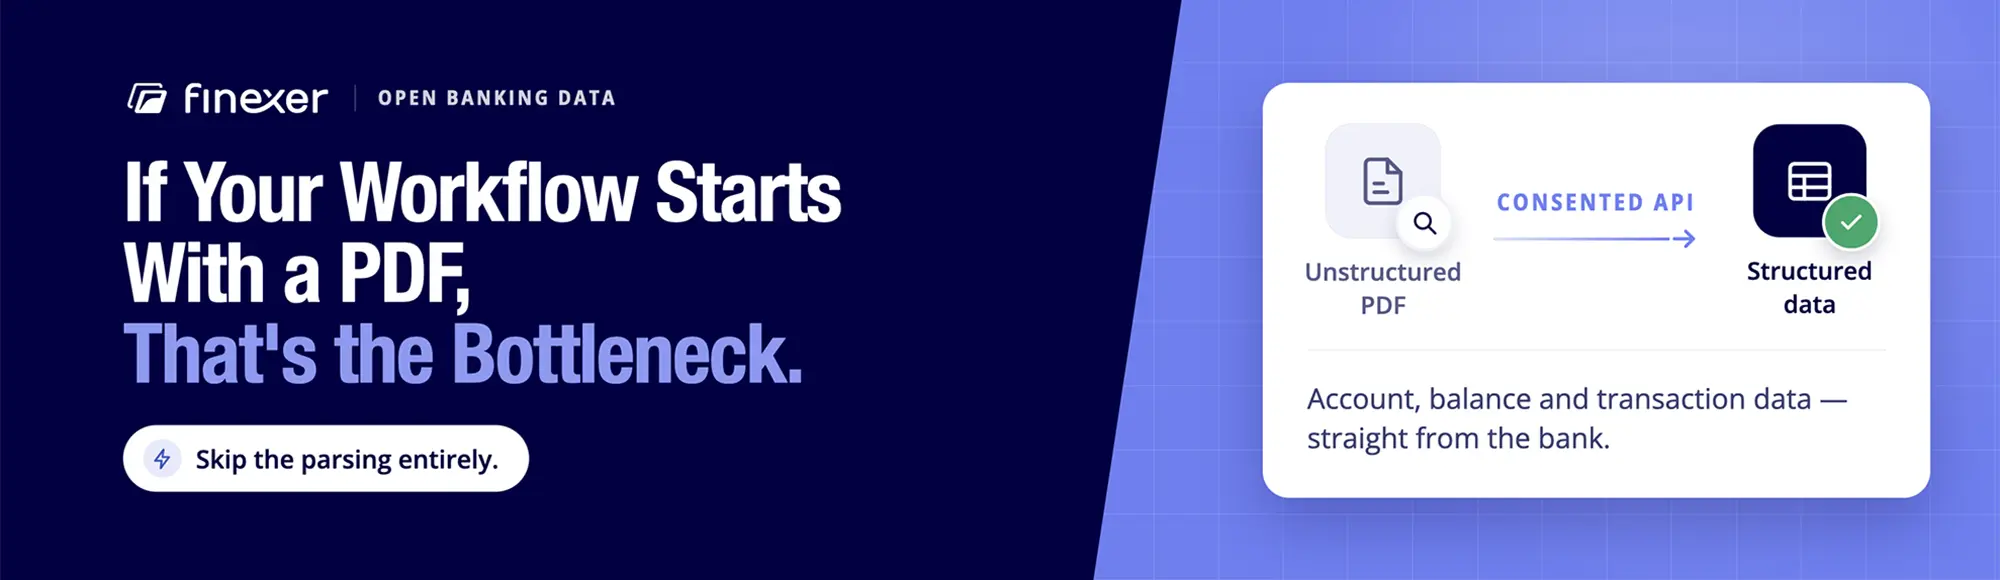
Extract data from bank statements without turning finance operations into a document-processing exercise. Comparing manual entry, CSV exports, PDF parsing, OCR and consented Open Banking access for bank statements, with practical guidance on accuracy, freshness, audit trails, data quality and direct banking data, makes better sense for UK accounting and platform workflows at scale.
Do Open Banking providers connect directly to banks or piggyback on other providers?
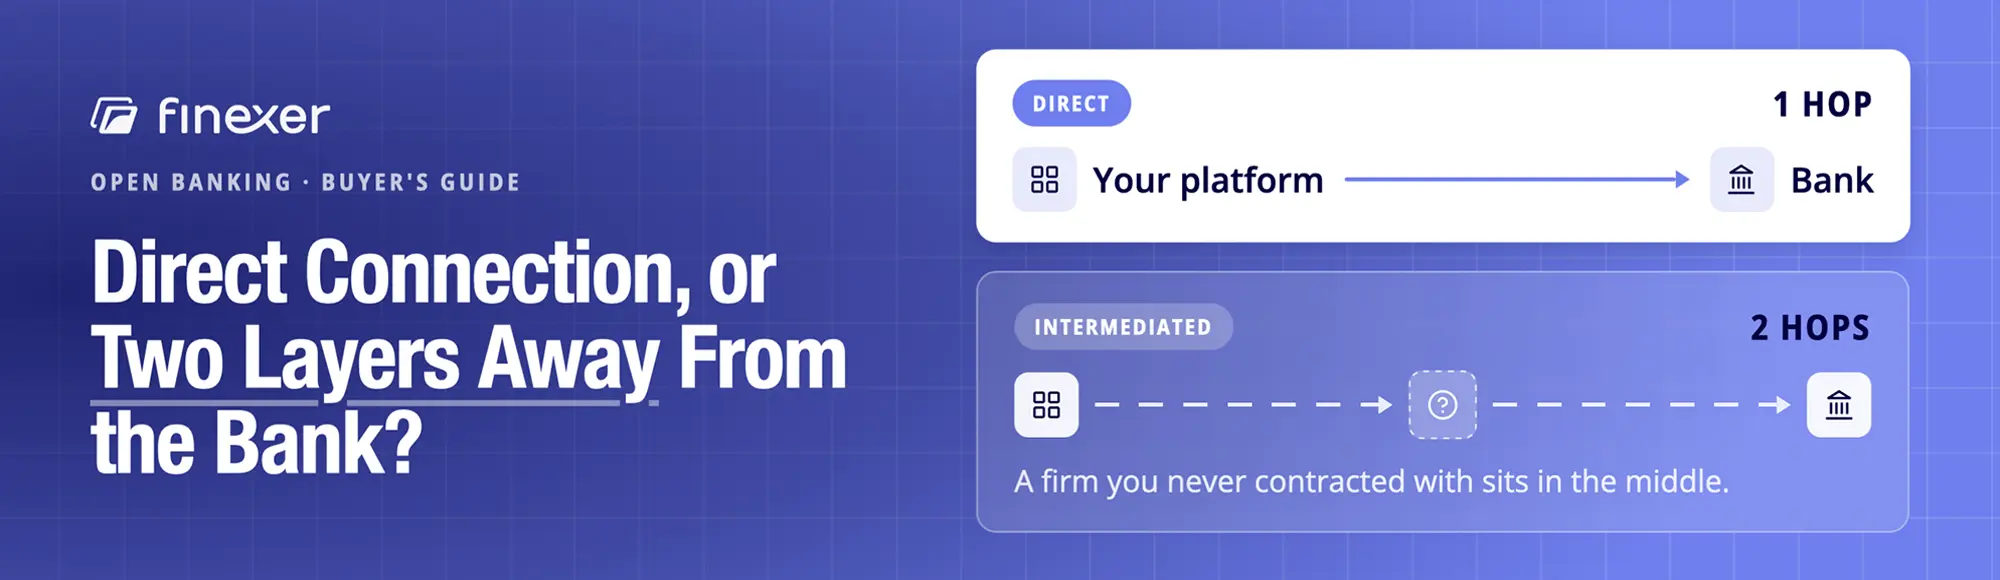
Some UK Open Banking providers hold a direct bank connection for AIS and PIS. Others resell a third party’s access, leaving you unable to diagnose faults or escalate outages. Learn the difference, how to verify it via the FCA Register, and why it matters for platforms relying on banking data.
How much transaction history can Open Banking return in the UK?
Open Banking transaction history varies by bank. Learn how provider requests, bank support and consent timing affect historical data.
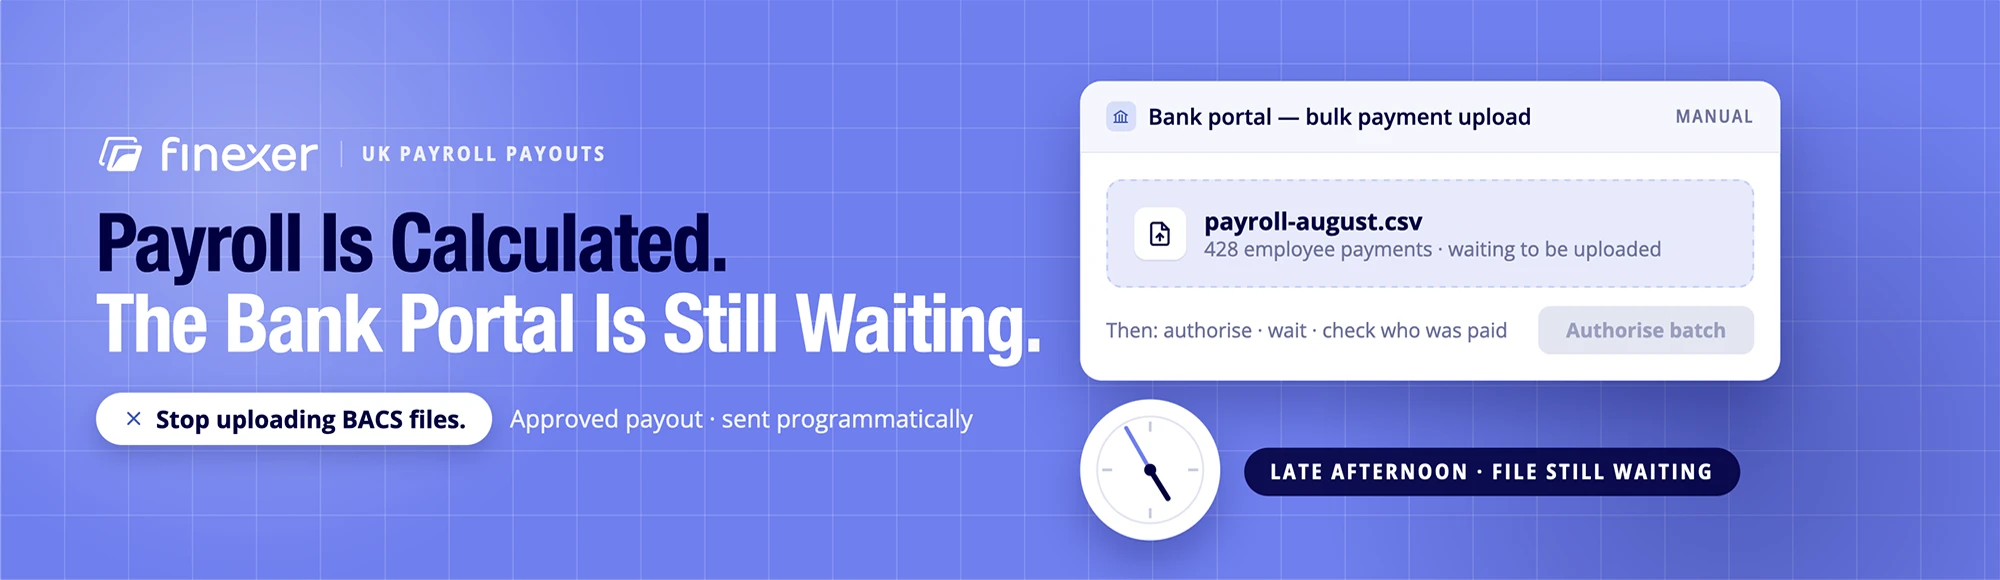
Automate Payroll Payments: What Changes After Payroll Is Approved
Automate payroll payments from an approved payroll payout, return the status of each employee’s payment and reconcile the completed payout against bank data. This guide explains where manual BACS work remains, how automated payroll software differs from payment automation and what finance and payroll teams should retain around approvals, bank details, exceptions and audit controls today.
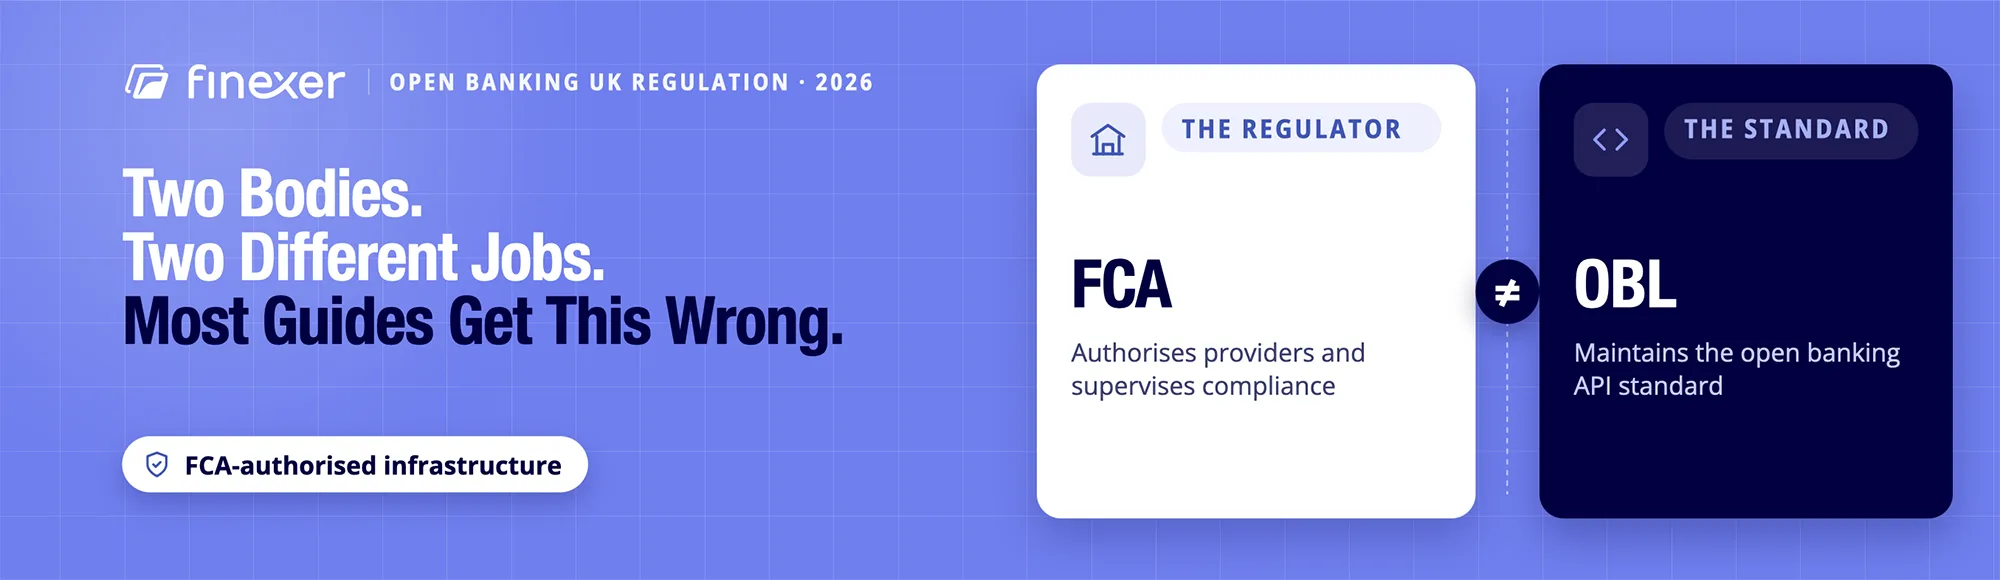
Open Banking UK Regulation: Essential 2026 Guide
Open banking UK regulation divides responsibility between the FCA and Open Banking Limited, with PSD2 as its legal foundation. This guide explains authorisation, AISP and PISP status, the 2026 regulatory changes, and what compliance leads and product managers should verify before building on an open banking provider.
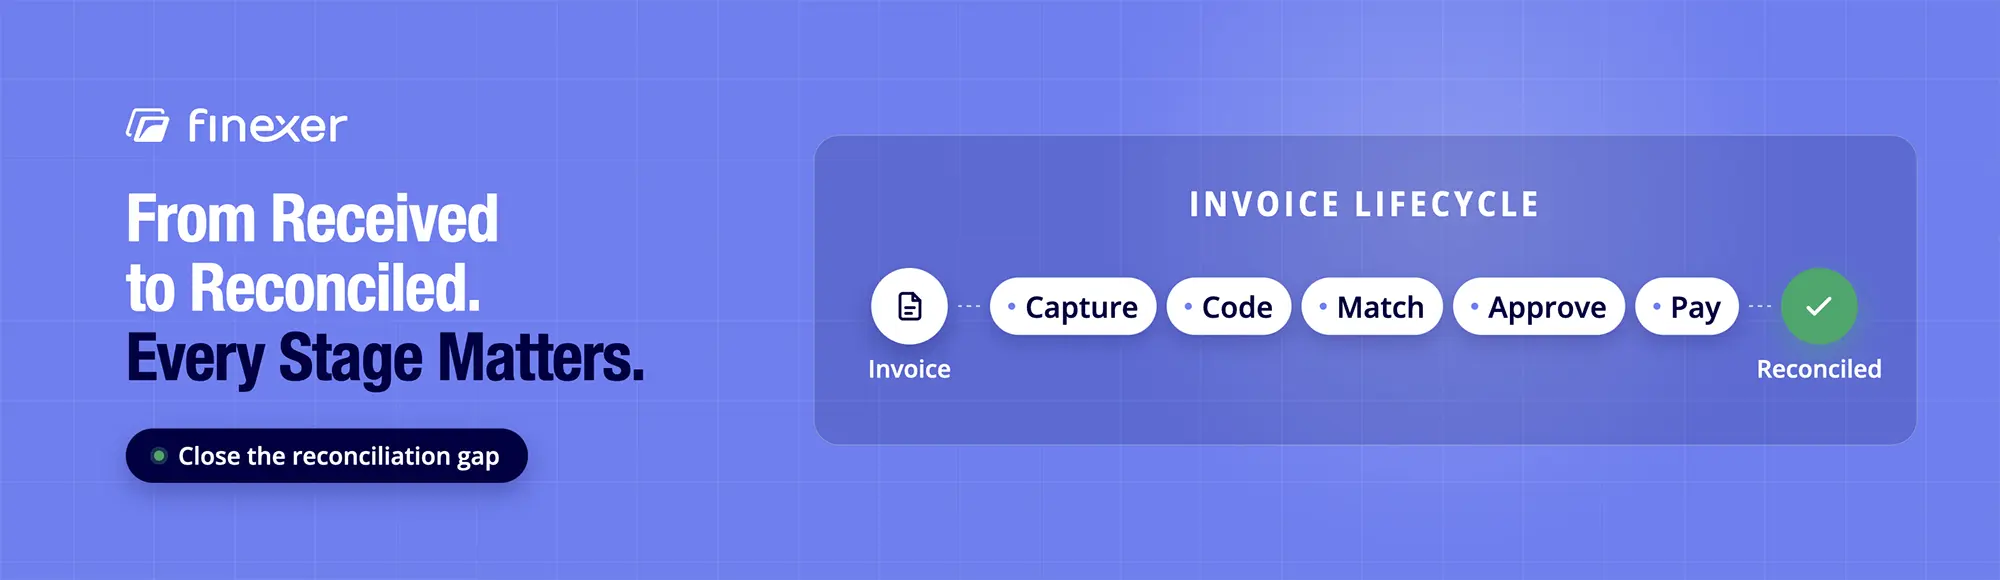
Invoice Processing: Complete UK Guide for 2026
Modern invoice processing turns received billing documents into approved, settled transactions. Understanding invoice processing in accounts payable requires evaluating data extraction, matching workflows and invoice processing solutions. By connecting workflow platforms to live banking data, finance teams eliminate manual keying while bridging the operational gap between payment execution and bank reconciliation.
Invoice Management Process: From Invoice Receipt to Reconciliation
An invoice management process takes an invoice from receipt through coding, matching, approval, payment and reconciliation. This article shows where invoice process automation can remove repetitive work, where finance teams still need controls, how to measure the workflow and how real-time banking data and payment references can connect invoices with the transactions that settle them.
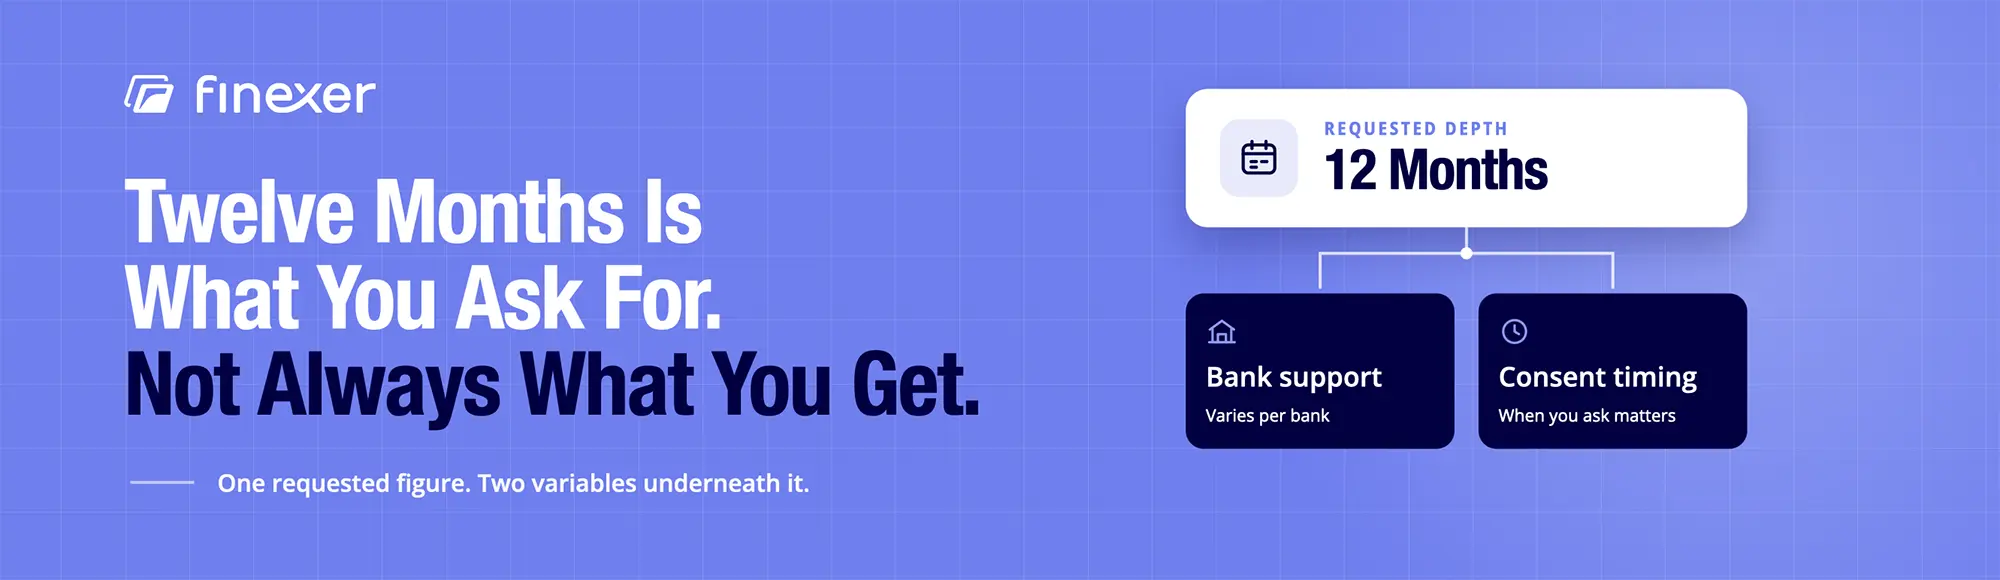
Which API Gives 12 Months of UK Banking Transaction History?
Most UK Open Banking APIs can request twelve months, but whether you receive it depends on the connected bank and on when you ask relative to consent.
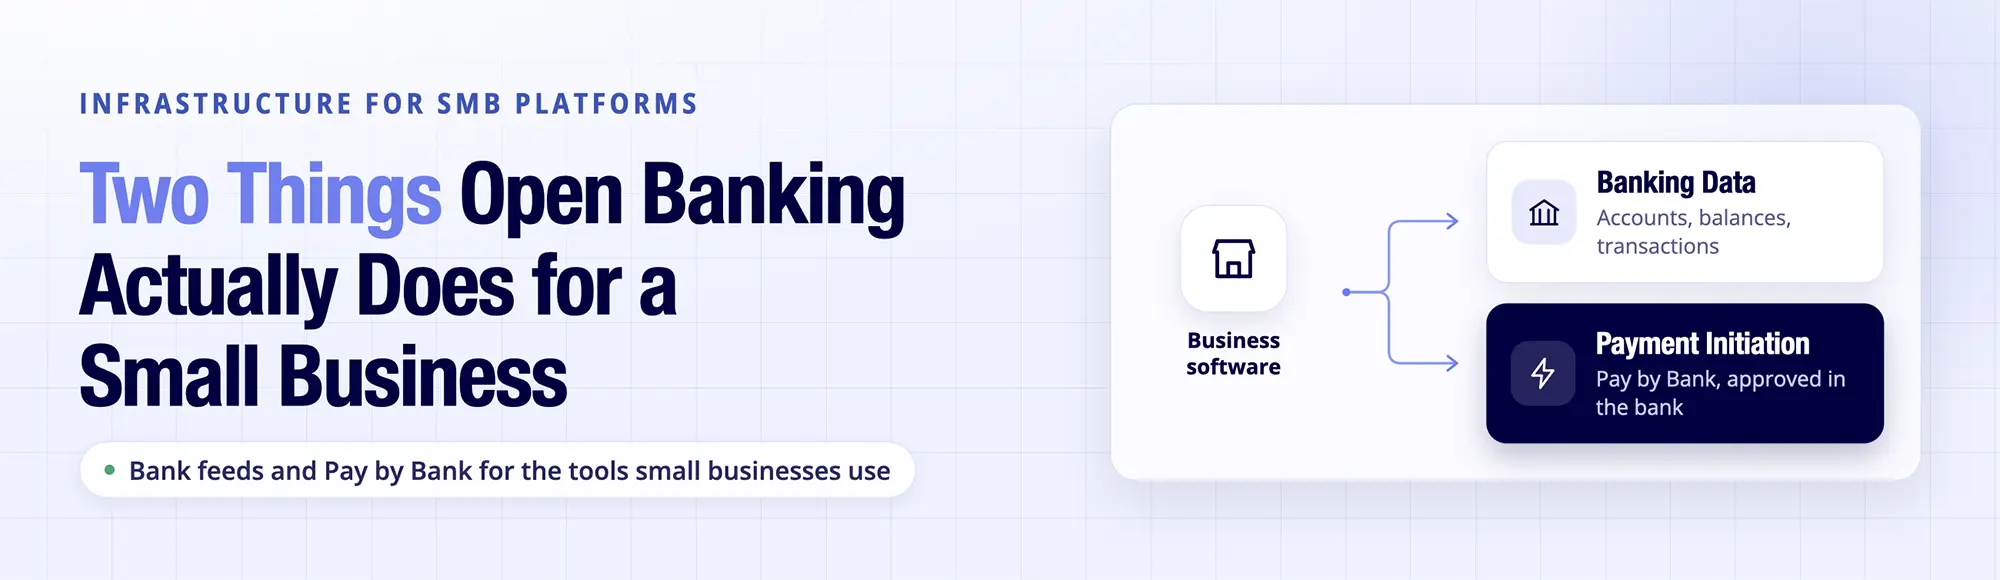
Open Banking for Small Businesses: A Practical UK Guide
Open banking for small business gives smaller firms access to banking data and account-to-account payments through regulated providers. This guide explains small business payment processing, Pay by Bank, reconciliation, cash visibility and open banking payment initiation, including what businesses need to get started and where platform providers such as Finexer fit into the picture.
EPOS Systems UK: 7 Things to Check Before You Buy
Comparing EPOS systems means looking beyond tills and software. This UK guide compares EPOS systems UK buyers consider, from retail to hospitality, then examines EPOS system benefits, payment costs, settlement and reconciliation. It also shows where UK Open Banking and Pay by Bank fit, without confusing payment infrastructure with the EPOS itself when choosing today.
Payroll Processing Software: 5 UK Tools Compared
Compare payroll processing software for UK practices and employers, including payroll processing software for accountants and payroll processing software for small business. This guide assesses HMRC recognition, bureau features, integrations, pricing models and the payment step after payroll. It also explains where payment execution, failed salary payments and reconciliation fit into the wider payroll workflow.
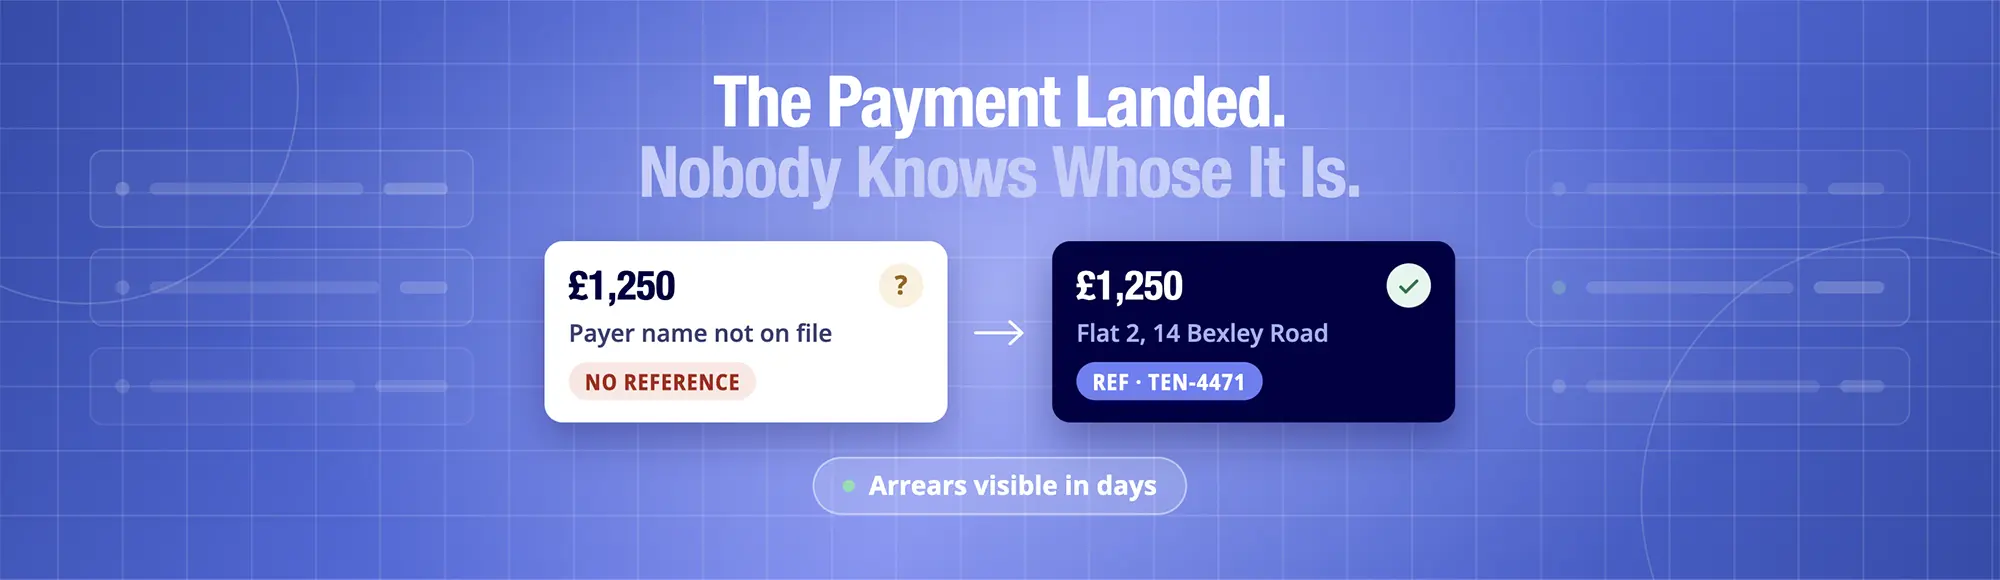
Rent Reconciliation: Why Matching Money to Tenancies Is Harder Than It Sounds
Rent reconciliation matches money received against rent due per tenancy, so arrears show up immediately rather than at month end. This guide covers why matching breaks down in practice, what makes it reliable, and how rental checks and a rental reference check fit into tenant screening separately, entirely apart from being confused with reconciliation itself.
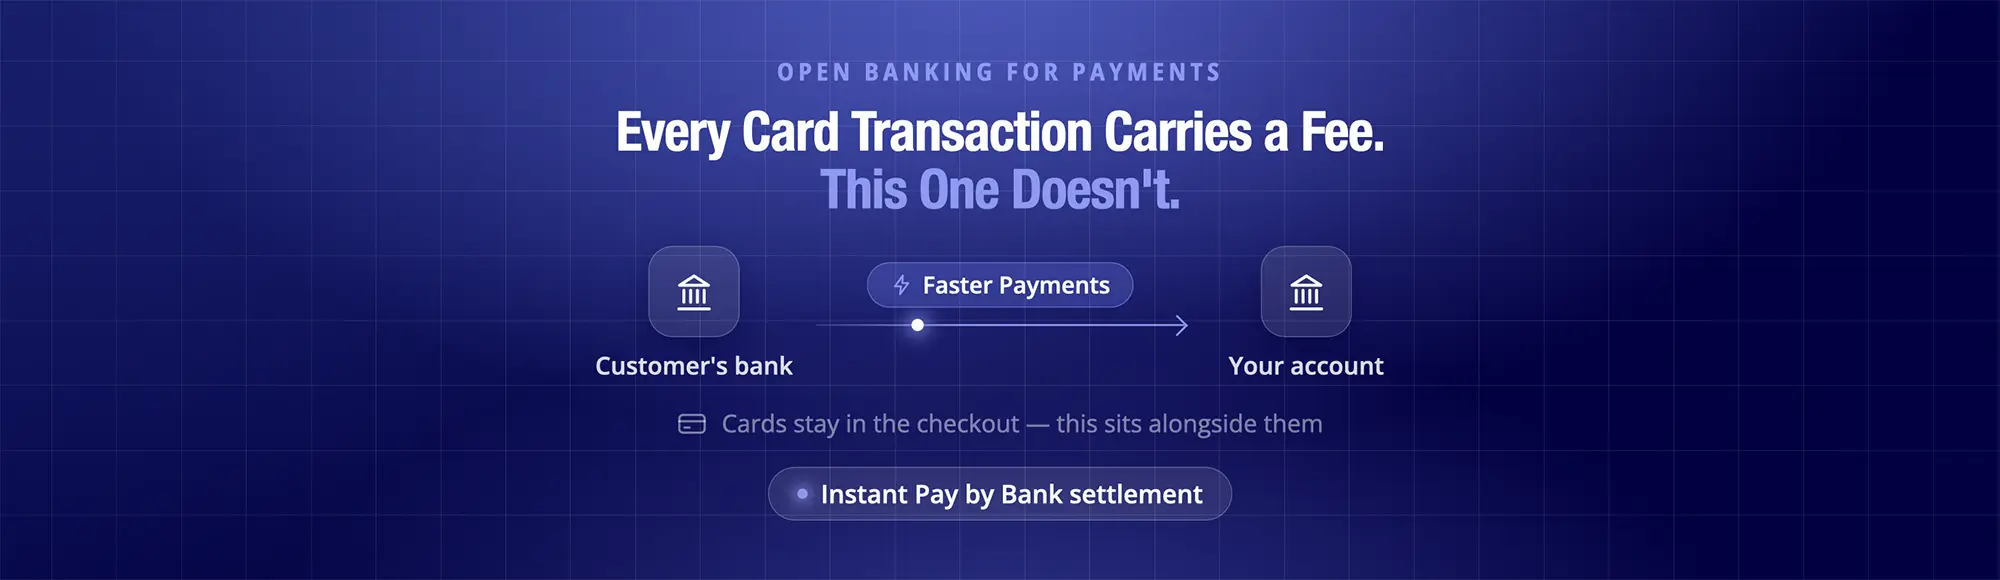
Open Banking for Payments: Proven Merchant Guide
Merchants evaluating open banking for payments want a direct comparison with cards on cost, settlement, and checkout experience. This guide covers how the open banking payment flow works, where it outperforms card rails, what its honest limitations are, and which UK business models get the most from it in 2026.
Affordability Check Rent: The Full Process, From First Enquiry to First Payment
Running an affordability check rent process well involves comparing evidence properly, not just collecting a payslip and moving on. This guide covers how UK letting agents assess affordability, why submitted documents fall short, how rent collection is done after move-in, through standing orders, Direct Debits or bank authorisation, and what rent collection services typically cover.
Proof of Banking Details: What Actually Counts, and What Doesn’t
Proof of banking details usually means a document or verified check confirming an account name, sort code, and account number belong to the named person or business. This guide covers what is proof of bank statement, what firms commonly accept and reject, and the alternative of verifying an account name directly against the bank record.