Introduction
Which is the cheapest online payment gateway for a UK merchant? The honest answer: it depends on your transaction volume, average basket size, card mix, and chargeback rate. The headline per-transaction percentage is the number providers advertise. It is rarely the number you pay.
The cheapest online payment processing decision requires understanding the full cost stack: interchange, scheme fees, gateway fees, chargeback fees, and settlement timing. Most gateway comparison pages skip most of these. This one does not.
For a broader view of online payment methods before you compare costs, see online payment systems.
Key Takeaways
- The cheapest online payment gateway by headline rate is not always the cheapest by actual cost ,interchange pass-through, chargeback fees, and blended rate structures all move the real number
- Payment gateway fees UK vary significantly between flat-rate and interchange-plus pricing models ,the right model depends on your volume and card mix
- Pay by Bank payments remove card interchange from the flow entirely, which is a structural cost reduction, not a marginal one
- Finexer is not a payment gateway ,it provides Open Banking payment initiation. Its relevance here is that Pay by Bank removes card processing costs entirely for transactions where customers use it
What Makes Up the Real Cost of Online Payment Processing?
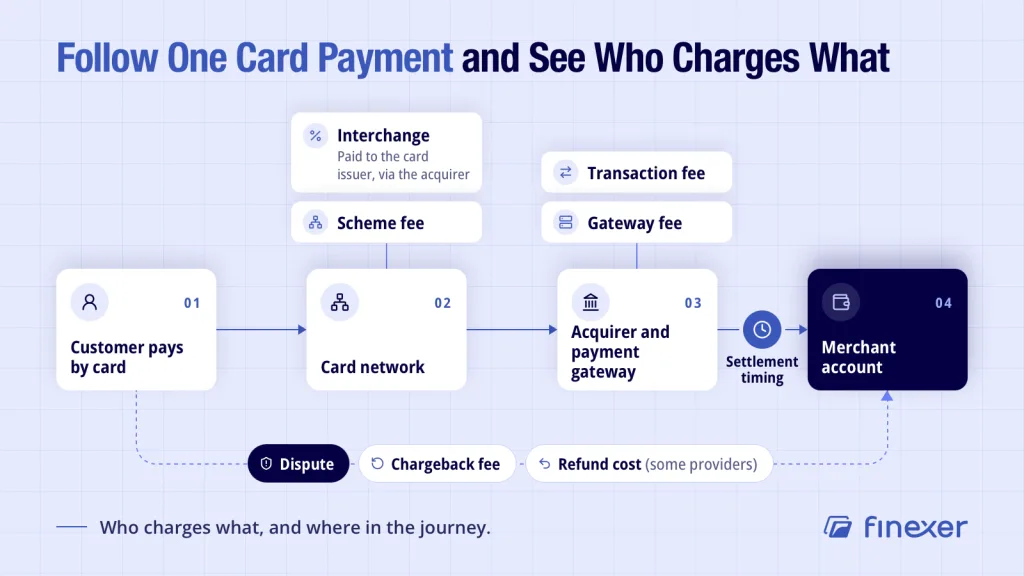
The cheapest online payment processing option depends on which costs you include. Most comparisons show the transaction fee only. Here is the full cost stack.
| Cost Element | What It Is | Who Charges It |
|---|---|---|
| Transaction fee | Per-transaction percentage or flat fee | Payment gateway provider |
| Interchange fee | Fee set by card networks (Visa, Mastercard) | Card issuer, via acquirer |
| Scheme fee | Card network participation fee | Visa or Mastercard |
| Gateway fee | Monthly or per-transaction platform fee | Payment gateway |
| Chargeback fee | Per-dispute handling fee, win or lose | Acquirer or gateway |
| Refund cost | Some providers charge for processing refunds | Varies by provider |
| Settlement timing | Delay between payment and funds in your account | Affects working capital |
The merchant service charge is the aggregate of interchange, scheme fees, and acquirer margin. It is what most merchants see on their monthly statement and what most cheapest payment processing comparisons ignore.
For EPOS-specific cost structures and how card terminal fees stack up, see epos systems uk.
Flat-rate vs interchange pass-through pricing
Flat-rate pricing charges a single percentage regardless of card type. It is predictable but can cost more for merchants with a low-risk, debit-heavy card mix. Interchange pass-through pricing charges the actual interchange cost plus a fixed acquirer margin. It is cheaper for merchants whose customers mainly use debit cards, and more expensive for merchants with a premium credit card mix.
Neither model delivers the cheapest payment processing outcome in every scenario. Knowing your card mix matters before choosing. High-debit merchants typically benefit from interchange pass-through. Mixed or credit-heavy merchants often find flat-rate cheapest payment processing simpler to budget against.
What Are the Main Payment Gateway Fees UK Merchants Pay?
The recognisable names in cheapest online payment gateway comparisons for UK merchants are Stripe, Square, SumUp, PayPal, and Worldpay. Published pricing below is drawn from each provider’s public UK pricing pages as of 2026. Pricing changes; verify directly before committing.
| Provider | In-Person Rate | Online Rate | Chargeback Fee | Pricing Model |
|---|---|---|---|---|
| Stripe | 1.5% + 20p | 1.5% + 20p (UK cards) | £15 per dispute | Flat-rate / interchange-plus |
| Square | 1.75% | 1.9% + 30p | No fee (limited disputes) | Flat-rate |
| SumUp | 1.69% | 2.5% | £10 per case | Flat-rate |
| PayPal | N/A | 2.99% + fixed fee (varies) | £20 per dispute | Flat-rate |
| Worldpay | Custom | Custom | Varies | Interchange pass-through |
For a detailed breakdown of SumUp’s full pricing structure including hardware costs, see sumup charges.
What the table does not show
Effective rate is what you pay after all fees. A provider with a 1.5% headline rate and a £15 chargeback fee becomes more expensive than a 1.75% flat-rate provider if you receive more than a handful of chargebacks per month. Card processing fees UK should be calculated on your actual numbers, not the headline.
How Do Card Processing Fees UK Compare to Pay by Bank?
This is the cost angle most cheapest online payment gateway comparisons miss entirely.
Card payments carry interchange fees on every transaction. Interchange is set by card networks (Visa, Mastercard) and passed through to you whether you see it explicitly or not. For UK consumer debit cards, interchange is regulated at a maximum of 0.2% per transaction. For credit cards, it rises to 0.3%. For commercial and corporate cards, it is unregulated and can reach 1.5-2% or more.
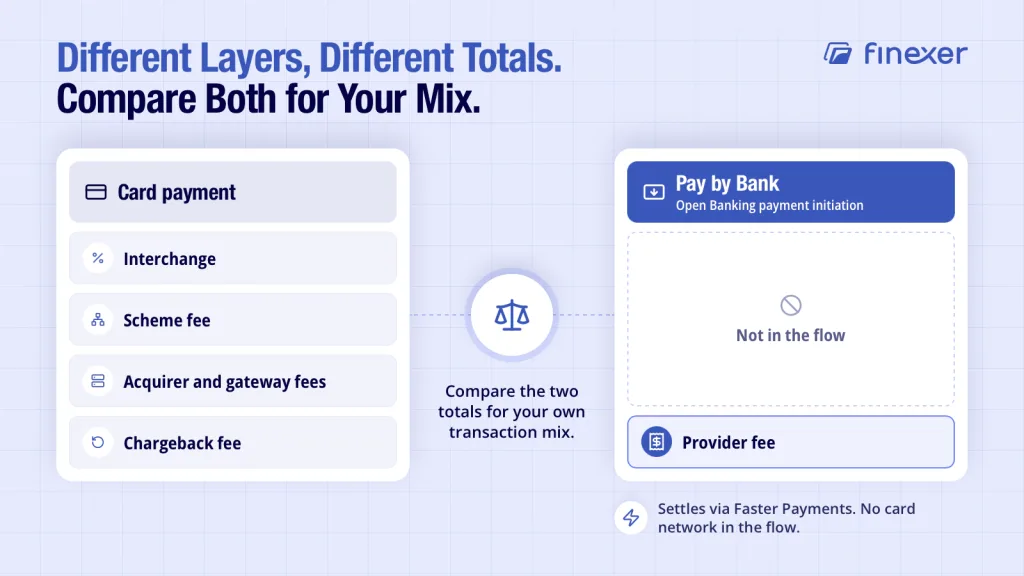
Pay by Bank payments move money account-to-account from the customer’s bank to yours, settling instant via Faster Payments. There is no card network in the flow. There is no interchange. There is no chargeback mechanism. The cost structure is fundamentally different, not incrementally lower.
For merchants where a significant portion of transactions could move to Pay by Bank, the arithmetic changes at the category level, not the basis-point level. For an overview of open banking payment methods and where they fit, see open banking payment methods.
How Do You Calculate Your Real Payment Gateway Cost?
A short worked method you can apply to your own numbers:
Step 1: Take your monthly card volume and multiply by your effective card processing rate (ask your provider for this, not the headline rate).
Step 2: Add your monthly chargeback fees (number of chargebacks x chargeback fee per case).
Step 3: Add any gateway platform or subscription fees.
Step 4: That is your monthly card processing cost.
Step 5: Identify what proportion of your transactions could be Pay by Bank eligible (high-value, one-off, B2B, or utility payments are the strongest candidates). Estimate the cost at usage-based Open Banking pricing for those transactions.
Step 6: The gap between Step 4 and Step 5 is the cost reduction available by adding Pay by Bank alongside cards. This is where cheapest payment processing is genuinely found for many merchants ,not by switching gateway, but by routing the right transactions to the right method.
This is not an argument to replace cards. It is an argument to understand where cheapest online payment processing actually comes from for your specific transaction mix.
When Is Cheapest the Wrong Criterion?
For merchants evaluating cheapest payment processing by rate alone, three costs are routinely underweighted.
Reliability cost
A gateway that is cheaper by 0.2% but goes down during peak trading hours costs more in missed revenue than the fee saving delivers. Uptime history matters more than SLA language. The Open Banking Limited ecosystem reported 99.80% weighted API availability in June 2026 (Open Banking Limited, openbanking.org.uk/api-performance). Ask any gateway provider for their equivalent figure.
Settlement speed cost
Next-day settlement is standard for most UK gateways. Instant settlement is available via Open Banking payment initiation. For businesses managing tight cash flow, a one or two-day settlement delay has a working capital cost that compounds across 12 months. That cost does not appear in any gateway comparison table.
Support cost
Cheapest online payment processing providers often have minimal support. A chargeback dispute, an integration failure, or a reconciliation problem handled through a ticketing system takes longer to resolve than one handled by a named technical contact. The time cost is real even if it does not appear on a fee schedule.
For a broader view of alternative payment methods and where they reduce cost structurally, see alternative payment methods.
How Does Finexer Fit This Comparison?
Finexer is not a payment gateway. It does not provide card acquiring, card acceptance, or card terminal infrastructure. Stating that clearly matters because a merchant choosing a cheapest online payment gateway for card transactions should not select Finexer as a gateway replacement.
Finexer’s relevance to this page is specific: its Payments product uses Open Banking payment initiation that settles instant via Faster Payments. Pay by Bank transactions initiated through Finexer carry no card interchange, no card scheme fees, and no chargeback mechanism. The cost structure is different at a fundamental level.
What Finexer Payments delivers for merchants adding Pay by Bank alongside card payments:
- Payment initiation via Open Banking: no card network, no interchange in the transaction flow
- Instant settlement via Faster Payments, directly into your account
- Per-payment webhooks confirming status in real time, not batched
- Most of the UK bank coverage across consumer, business, and challenger accounts
- Transparent pricing with no hidden charges
- FCA-authorised PISP (FRN 925695) under the Payment Services Regulations 2017
- PCI DSS-compliant infrastructure
- 3-5 weeks onboarding support for mid-market SaaS and fintech platforms
Use cases where Pay by Bank reduces cost most
- EPOS: High-value in-person purchases where interchange on a £500+ transaction is material
- Utility Billing: Recurring and one-off utility payments where card interchange on large bills compounds monthly
- E-commerce merchants: B2B or high-value consumer orders where chargeback risk is highest, and Pay by Bank eliminates it
Bottom Line
The cheapest online payment gateway by headline rate is rarely the cheapest by effective cost. Interchange pass-through, chargeback fees, and settlement timing all affect the real number. For card transactions, the comparison between Stripe, Square, SumUp, PayPal, and Worldpay depends on your volume, card mix, and dispute rate.
For transactions where Pay by Bank is a genuine option, the cost structure changes entirely because card interchange is not in the flow at all. Calculate your effective rate first. Then identify which part of your transaction mix benefits most from cheapest online payment processing via Open Banking.
What is the cheapest online payment gateway for small UK businesses?
For card-based cheapest online payment processing, Square (1.75% in-person) and SumUp (1.69% in-person) offer competitive flat rates with no platform fees on standard plans. Stripe offers 1.5% + 20p per transaction with interchange-plus available for higher volumes. The cheapest option depends on your card mix, chargeback rate, and average transaction value. Verify current pricing directly with each provider before committing.
What are the main payment gateway fees UK merchants should compare?
The full cost stack for payment gateway fees UK includes: transaction rate, interchange pass-through or blended rate, scheme fees, platform or gateway fees, chargeback fees per dispute, refund processing fees where charged, and settlement timing. Most cheapest online payment gateway comparisons show only the transaction rate. Your effective rate, calculated from all of these, is the number that matters.
What is the cheapest card payment machine in the UK for in-person transactions?
The cheapest card payment machine in the UK for upfront cost is SumUp Air at £19 + VAT, with a 1.69% per-transaction rate. Square Reader is free in some promotions with a 1.75% rate. For high-volume merchants, Worldpay’s interchange-plus model may produce a lower effective rate despite higher hardware costs. The cheapest card payment machine in the UK in total cost depends on your monthly volume, not just the hardware price.
How do card processing fees in the UK compare to Open Banking payment costs?
Card processing fees in the UK include interchange (regulated at 0.2% for consumer debit, 0.3% for consumer credit, unregulated for commercial cards), scheme fees, and acquirer margin. Pay by Bank via Open Banking carries no interchange, no scheme fees, and no chargeback fee. For merchants where a meaningful share of transactions can move to Pay by Bank, the cost difference is structural rather than marginal.
Pay by Bank removes card interchange from the transaction entirely. That is not a fee reduction. It is a different cost structure.
Explore with AI
About the Author
Ravi Ranjan
Ravi Ranjan is Co founder & CEO of Finexer